Monday
September 28, 2026
Home Blog Page 2

The Vacuum Bhutan Is Racing to Fill: Buddhist Diplomacy Ahead of a Two-Dalai-Lama Future

By: Khushbu Ahlawat, Consulting Editor, GSDN
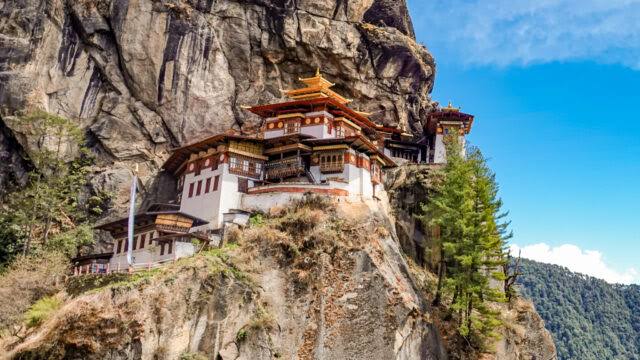
Reading Bhutan’s recent Buddhist outreach: Source Internet

A Himalayan kingdom of fewer than 800,000 people is building religious infrastructure, hosting royal visits, and convening Buddhist gatherings at a pace with no precedent in its recent history. A temple complex broke ground in Lumbini in June. A shrine went up in Rajgir last September. Land has been earmarked for a temple and guest house in Varanasi, near Sarnath, where the Buddha delivered his first sermon. Sri Lankan Prime Minister Harini Amarasuriya’s five-day visit to Bhutan this past August, capped by the keynote at Thimphu’s first Global Conscious Food Systems Summit, was the latest entry in that pattern, not an isolated courtesy call. None of this is happening in a vacuum — except that, in the most literal sense, it is. A real vacuum is opening in the leadership of world Buddhism, in the very institution that has anchored Himalayan Buddhist authority for nearly a century, on a timeline nobody controls. Bhutan appears determined to be ready for it before anyone else is.

The clock that is actually running

The proximate cause of that vacuum is not abstract. The 14th Dalai Lama, Tenzin Gyatso, turned 90 in July 2025, and in the days before his birthday he made a declaration that has since reshaped the succession question from a distant hypothetical into an active geopolitical dispute: his reincarnation, he said, will be recognised solely by the Gaden Phodrang Trust, the nonprofit institution he established for that purpose, and by no other authority. Beijing’s response came within hours. A Chinese foreign ministry spokesperson reiterated that any reincarnation of the Dalai Lama, like that of the Panchen Lama, must be selected by drawing lots from a golden urn under the supervision of the central government — the same 2007 regulation, “Order No. 5,” that requires state approval for the recognition of all Tibetan Buddhist reincarnations on Chinese soil. When India’s minister for minority affairs, Kiren Rijiju, publicly backed the Dalai Lama’s position, Beijing warned New Delhi to “be prudent” on what it called a highly sensitive matter, and India’s foreign ministry retreated to studied neutrality, saying only that the government does not take positions on matters of religious belief.

The likeliest outcome, according to most scholars tracking the dispute, is not a resolved succession but a contested one: two rival 15th Dalai Lamas, one recognised by the Tibetan exile establishment operating out of Dharamsala and one installed through Beijing’s state apparatus, each claiming legitimacy before a global following that will have to choose. That prospect carries particular weight for the countries clustered along the Himalayan arc — India, Nepal, Mongolia and Bhutan — where nearly half of the Tibetan exile community still lives, mostly in India, and where the institutional authority the Dalai Lama has held since fleeing Tibet in 1959 has functioned as a kind of gravitational centre for Vajrayana Buddhist practice across the region. Some analysts have gone further, suggesting the next Dalai Lama could plausibly be identified on Indian soil, conceivably even in Tawang — the birthplace of the sixth Dalai Lama and a district China formally claims as part of its own territory — a scenario that would fuse the religious succession dispute directly onto the unresolved India-China border question.

Bhutan sits inside all of this without being a direct party to it, and that position — adjacent to the dispute but not implicated in it — is precisely what its recent diplomacy has been built to exploit.

Why Bhutan, specifically, can do this

The detail that gets lost in most accounts of Bhutan’s Buddhist outreach is that Bhutanese state Buddhism is not the Dalai Lama’s own school. Bhutan’s national religion, formalised under the 17th-century unifier Zhabdrung Ngawang Namgyal and enshrined today in the 2008 constitution, is the Drukpa Kagyu lineage — a distinct branch of Tibetan Vajrayana Buddhism from the Dalai Lama’s Gelug tradition, with its own historical hierarchy, its own monastic institutions, and its own claim to religious authority that predates and does not depend on Lhasa’s Gelug establishment. That distinction matters enormously for how Bhutan can behave right now. A country whose state religion were itself Gelug, or that hosted the Dalai Lama’s own exile institutions the way India does, would face an almost impossible choice as the succession dispute sharpens — recognise the Gaden Phodrang Trust’s candidate and risk Beijing’s fury, stay silent and risk its own religious community’s anger, or attempt open neutrality and satisfy no one. Bhutan, by contrast, can expand its own religious infrastructure, host interfaith gatherings, and position its monarchy as a custodian of Himalayan Buddhist heritage without ever being asked to rule on who the next Dalai Lama actually is, because that question sits outside its own lineage’s chain of authority.

The Global Peace Prayer Festival that Bhutan hosted in Gelephu in November 2025 is the clearest illustration of what this buys Thimphu. The ten-day gathering brought together lamas, scholars and practitioners from across Buddhism’s schools — including figures close to the Dalai Lama himself — under prayers led by Bhutan’s own Chief Lama, with relics from the Piprahwa-Kapilavastu excavation brought over from India to lend the event additional weight. A festival like that is not a neutral act in the ordinary sense; convening rival Buddhist constituencies under one roof, at a moment when those constituencies are edging toward an institutional split, is itself a form of influence-building. But it is influence Bhutan can accumulate specifically because nobody needs to ask the Bhutanese monarchy whose side it is on in a succession dispute that, doctrinally, is not its dispute to settle.

The economic engine behind the religious outreach

None of this soft-power accumulation would carry the weight it currently does without the domestic project underwriting it: the Gelephu Mindfulness City, the special administrative region King Jigme Khesar Namgyel Wangchuck unveiled on Bhutan’s 116th National Day in December 2023 and which has since become the organising frame for almost everything else in Bhutanese foreign policy. GMC is an unusually large bet for a country this size — a masterplan spanning more than a thousand square kilometres of southern Bhutan along the Indian border, pitched to investors at a scale approaching $15 billion, designed around eleven mandala-inspired neighbourhoods by the Bjarke Ingels Group, and structured as a “one country, two systems” jurisdiction with its own legal code, drawing partly on Singaporean commercial law, its own executive and legislature operating under the King’s direct guidance. Its first completed sacred landmark, the Ugyen Norlha Chorten, dedicated to a manifestation of Guru Rinpoche associated with prosperity, was a deliberate signal that this is meant to be read as spiritual infrastructure as much as economic infrastructure — an attempt to make Bhutan’s Buddhist identity and its development strategy the same project rather than two competing ones.

The urgency behind that fusion is domestic and demographic as much as geopolitical. Roughly 71,000 Bhutanese — about a tenth of the country’s population — have emigrated in recent years, driven by the same pull factors reshaping small economies everywhere: better wages abroad, urban aspiration, exposure to a wider world through social media that an isolated Himalayan kingdom spent decades trying to manage carefully. Bhutan’s total fertility rate has fallen to around 1.4 children per woman, a level associated with long-term population decline. For a state whose foreign policy, security doctrine and even its signature Gross National Happiness framework have always rested on the idea that Bhutanese culture and religious identity are themselves the country’s chief strategic asset — the thing that has kept a nation of fewer than a million people sovereign between two Asian giants — a hollowing-out of that identity through emigration is not a soft social problem. It reads, in Thimphu’s own framing, as an existential one. GMC’s spiritual-economic hybrid model is meant to answer both problems with one instrument: give young Bhutanese a reason to stay by building a globally connected, high-value economic zone at home, and give the outside world’s Buddhist tourism and investment interest a specific place to land, rather than leaving Bhutan simply exporting its youth while other countries harvest its cultural cachet.

A fragile kind of leverage

It would be a mistake to read Bhutan’s Buddhist diplomacy as a bid for the kind of religious leadership India, Thailand or China itself has invested in — each of those states has poured far greater resources into monastic education, scholarly institutions and multilateral Buddhist convening than Bhutan’s more modest, temple-by-temple approach can match, and Bhutanese officials have never suggested they are trying to compete on that scale. What Bhutan appears to want instead is narrower and more achievable: enough institutional presence at Buddhism’s sacred sites, enough convening credibility, and enough diplomatic diversification beyond its overwhelming dependence on India, that the kingdom’s survival does not rest on any single relationship or any single unresolved dispute working out in its favour.

That is also, precisely, why the strategy carries real fragility. Bhutan’s neutrality on the succession question is sustainable only as long as the dispute stays where it currently is — a war of statements and legal claims rather than a live crisis with a named successor on the ground. If the next Dalai Lama is in fact identified somewhere in India, as several analysts now consider plausible, Beijing’s warnings to New Delhi about “interference” in Tibet-related matters would almost certainly extend to any Himalayan state seen as legitimising that recognition through its own religious convening — a category Bhutan’s festivals and temple-building have deliberately, if implicitly, placed it in. Bhutan’s own unresolved boundary negotiations with China, still unsettled in areas adjacent to the Doklam plateau where Indian and Chinese forces faced off in 2017, give Beijing additional leverage over how much diplomatic room Thimphu actually has whenever a genuinely hard choice arrives. The outreach documented over the past three years has been possible precisely because the vacuum it is filling has remained, so far, a vacuum of anticipation rather than a fully realised institutional rupture. The real test of Bhutan’s Buddhist diplomacy will not be this year’s temple groundbreakings or peace festivals. It will be the moment, whenever it comes, when the 14th Dalai Lama’s passing turns two competing claims to a still-empty title into two actual claimants — and Thimphu, for the first time, has to decide whether convening everyone is still an option, or whether survival now requires choosing a side.

Bhutan’s Buddhist diplomacy, then, is best understood not as a finished strategy but as a wager placed against a clock the kingdom does not control. Every temple groundbreaking, every royal visit to Ulaanbaatar or Hanoi, every prayer festival that manages to seat Dalai Lama loyalists and other Buddhist schools at the same table is another brick laid while the foundation underneath — the assumption that the succession question can remain unresolved a while longer — still holds. That assumption has an expiry date, even if nobody can name it precisely: the 14th Dalai Lama is 90, and the moment of his passing will convert a dispute conducted so far in statements, regulations and diplomatic warnings into one conducted through actual, competing claimants. When that happens, the very quality that has made Bhutan’s outreach possible — its doctrinal distance from the fight, its ability to convene without having to choose — will be tested in a way it has not yet been. Gelephu Mindfulness City, the economic engine meant to give this soft-power project material weight, faces its own test on a similar horizon: whether a $15 billion vision drawn on paper by Danish architects can actually slow the emigration of a tenth of Bhutan’s population before the country’s demographic base erodes further. Neither test can be won through diplomacy alone, and neither can be delayed indefinitely. What Bhutan has built in three years is real, and it has genuinely expanded the kingdom’s room to manoeuvre between two much larger neighbours. Whether that room survives contact with an actual, contested succession — rather than the anticipation of one — is the question Thimphu has bought itself time to prepare for, but not the power to postpone.
What went Wrong in USA’s planning for the Iran War?  

By : Sonalika Singh, Consulting Editor, GSDN

USA-Israel-Iran war : Source Internet

The war with Iran exposed a gap between Washington’s expectations before the conflict and the strategic reality that emerged after it began. What was expected to be a relatively controlled military campaign developed into a prolonged confrontation in which Iran demonstrated an ability to impose costs on U.S. forces, disrupt regional military infrastructure and threaten the economic foundations of the conflict. The central problem was not that the United States lacked military power. Rather, its planning appears to have underestimated how Iran would adapt, how vulnerable forward-deployed forces could become, and how quickly a limited operation could expand into a wider contest involving military, political and economic pressures. 

One of the most important planning errors was the tendency to generalize from the earlier 12-day Iran-Israel war. That conflict demonstrated the effectiveness of modern air power and precision strikes against Iranian targets, and it may have encouraged the assumption that a larger U.S.-led campaign could achieve decisive results quickly. But a direct confrontation between Iran and the United States was fundamentally different. Israel and the United States have different geographic positions, military structures and regional vulnerabilities. The United States operates through a network of bases, logistics hubs, aircraft, tankers, surveillance platforms and command facilities spread across the region. Iran therefore did not need to defeat American forces in a conventional sense. It only needed to make the infrastructure supporting U.S. operations sufficiently vulnerable and costly. 

This distinction became particularly important as Iran shifted its focus from Israel to the U.S. military presence in the region. American bases and associated facilities became central targets. The strategic logic was straightforward: rather than attempting to destroy the most sophisticated U.S. combat aircraft in direct engagements, Iran could attack the broader system that makes American power projection possible. Radar installations, communications nodes, runways, fuel supplies, ammunition storage, command centers and logistics facilities all became potential pressure points. This challenged an assumption that American forces could operate from regional bases with a high degree of sanctuary while concentrating offensive power against Iran. 

The vulnerability of forward bases was therefore a major weakness in the original planning concept. U.S. military strength depends partly on its ability to move large quantities of people, weapons, fuel and equipment through established regional networks. Those networks are efficient under conditions of air superiority and secure access. They become more complicated when an adversary can threaten the bases and routes on which they depend. Iran did not need to permanently eliminate these facilities to create disruption. Repeated strikes, alerts, damage, temporary closures and the need to disperse aircraft and personnel could impose costs while reducing operational efficiency. The resulting pressure was not necessarily visible through traditional measures of battlefield victory, but it affected the sustainability of the campaign. 

Another apparent miscalculation concerned Iran’s military adaptation. Iran’s missile and drone capabilities were not new, but the war demonstrated the importance of viewing them as part of a broader operational system rather than as isolated weapons. Precision strikes against military infrastructure, combined with drones, missiles and efforts to challenge air-defence and surveillance networks, allowed Iran to contest the environment in which U.S. forces operated. Even when American forces retained significant defensive and offensive capabilities, the need to intercept incoming weapons consumed resources and required continuous attention. This created an asymmetric dynamic: relatively inexpensive systems could force a technologically superior opponent to spend substantial resources on defence. 

The conflict also raised questions about the assumption that advanced U.S. air power could guarantee uncontested operations throughout the campaign. Destroying or suppressing elements of an opponent’s air-defence network does not automatically eliminate the broader challenge. Modern air defence is increasingly distributed, mobile and difficult to neutralize completely. Radar, communications, launchers, and command systems can be relocated, concealed, or reconstituted. If an adversary retains enough of this architecture to threaten aircraft and support infrastructure, the attacking side must devote additional resources to maintaining air superiority. This can complicate operational planning and extend the duration of a campaign. 

A second major weakness was the apparent underestimation of Iran’s ability to absorb military pressure. Planning that assumes rapid political or social breakdown can become dangerous when the target government can present the conflict as a struggle for national survival. Expectations of domestic instability or protests may not account for the rally-around-the-flag effect created by external attacks. Military pressure can weaken a government, but it can also encourage segments of the population to prioritize national sovereignty over domestic political grievances. In Iran’s case, the continuation of resistance demonstrated why military planners cannot treat internal political opposition as an automatic indicator of imminent state collapse. 

The same problem applies to the wider regional environment. A conflict with Iran cannot easily be separated from the network of states and armed groups connected to the country’s regional strategy. Attacks on U.S. forces created the possibility of a wider escalation involving partners and aligned groups. This increased the number of potential targets and forced Washington to consider not only operations inside Iran but also the protection of personnel and infrastructure across several countries. The regional military footprint that provides the United States with strategic reach can therefore become a liability when an adversary could threaten multiple locations simultaneously. 

The war also exposed the limits of assuming that regional partners will automatically provide unrestricted military access. Countries hosting U.S. forces have their own security concerns, domestic politics and relationships with Iran and other regional actors. During a major conflict, governments may seek to limit the use of their territory or airspace to reduce the risk of retaliation. This creates an important distinction between having military facilities in a region and having complete freedom to use them in a war. Effective planning must account for the political conditions surrounding bases, not merely their physical availability. 

Perhaps the most consequential strategic miscalculation involved the economic dimension of the conflict. Military planners can focus on targets, aircraft, missiles and bases while underestimating how quickly war affects energy markets and domestic economies. The possibility of disruption around the Strait of Hormuz was particularly significant because of its importance to global energy flows. Any sustained threat to shipping through the Strait can increase oil prices, insurance costs and transportation risks. Higher energy prices can then feed into inflation and increase political pressure at home. A military campaign that appears manageable in operational terms can therefore become far more difficult when its economic consequences accumulate. 

This highlights a broader problem with measuring success in a modern war. Destroying enemy targets is only one component of strategic effectiveness. A campaign must also consider whether the opponent can continue fighting, whether military access can be sustained, whether economic costs remain manageable, and whether political objectives remain achievable. If the United States can inflict severe damage but cannot prevent the adversary from imposing persistent costs, the relationship between tactical success and strategic success becomes uncertain. 

There are also lessons about decision-making itself. Complex military operations require commanders and policymakers to test assumptions rather than simply reinforce them. If early assessments strongly favor a short campaign, there is a risk that contradictory intelligence will be discounted or interpreted as temporary resistance. Effective planning requires serious consideration of alternative scenarios prolonged missile attacks, attacks on bases, disruption of logistics, restrictions by regional partners, economic shocks and the possibility that the adversary adapts faster than expected. The ability to challenge optimistic assumptions is especially important when political leadership has already committed itself to a particular strategic narrative. 

The Iran war therefore raises a larger question about the sustainability of the U.S. model of power projection. For decades, American military strategy has benefited from an extensive network of overseas bases and logistical infrastructure. This system provides reach, speed, and flexibility, but it also creates identifiable dependencies. An adversary that cannot match the United States aircraft for aircraft may instead target the infrastructure that allows those aircraft to operate. The challenge is not unique to Iran. Other major powers could study the same vulnerabilities and develop their own approaches to disrupting forward-deployed forces. 

The implications extend beyond the Middle East. The experience offers lessons for any future confrontation involving a technologically sophisticated adversary with missiles, drones, cyber capabilities, long-range fires, and the ability to target logistics. Dispersed forces, hardened infrastructure, mobile command systems, resilient communications, protected fuel and ammunition supplies, alternative logistics routes and greater reliance on unmanned systems may become increasingly important. So will the ability to sustain operations without depending excessively on a small number of vulnerable bases. 

Diplomacy is another part of the lesson. Military planning often treats diplomacy as something that follows from battlefield developments, but in a geographically complex conflict, political arrangements can directly affect military effectiveness. Access to agreements, regional de-escalation mechanisms, communication channels, and contingency planning with host governments can reduce the risk that military operations become constrained by political developments. The ability to end a conflict on acceptable terms is also part of strategic planning and should be considered before hostilities begin. 

Ultimately, what went wrong in U.S. planning was not simply an underestimate of Iranian military capability. It was a broader mismatch between the assumptions of a short, controlled campaign and the realities of a contested regional war. Washington appears to have underestimated Iran’s ability to shift the focus of the conflict toward U.S. vulnerabilities, sustain missile and drone pressure, exploit the dependence of American forces on regional infrastructure, and generate wider economic and political costs. 

The United States retained substantial military advantages and the ability to conduct powerful offensive and defensive operations. Yet the war demonstrated that overwhelming technological superiority does not automatically translate into control over the strategic environment. Iran did not need to defeat the United States symmetrically. By targeting the foundations that support American power projection, it could impose costs and complicate the campaign. 

The broader lesson is therefore about expectations. The ability to start a war is not the same as the ability to control its duration, geography, or consequences. Future U.S. planning will need to account more carefully for adversary adaptation, base vulnerability, regional political constraints, economic interdependence and the possibility of prolonged conflict. The Iran war shows that in modern warfare, the decisive question is not only what an army can destroy, but whether it can sustain its own system of power while preventing the opponent from changing the terms of the conflict. 

We call it “Mantra”, They call it Positive Affirmations

0

By: Anamika Tiwari, Guest Author, GSDN

Are we discovering something new—or rediscovering the wisdom of our ancient Indian Knowledge Systems?

In today’s world, “Positive Affirmations” have become a popular term for building confidence, changing thought patterns and developing a positive mindset. People repeat statements such as:

“I am capable.”
“I am strong.”
“I believe in myself.”
“I can overcome challenges.”

These practices are often presented as modern techniques for psychological well-being.

But when we look deeper into the Indian Knowledge Systems (IKS), we find that the idea of using sound, repetition, contemplation, self-reflection and powerful statements to shape the mind has a very long history.

We have called many such practices Mantra, Japa, Svādhyāya, Sankalpa, Smarana and contemplation.

The terminology may be different. The philosophical frameworks are different. And we should not assume that a modern psychological technique and a traditional mantra are exactly the same thing.

But there is an important question worth asking:

Have we become so accustomed to looking towards the West for new ideas that we sometimes fail to recognise the wisdom within our own traditions?

MANTRA — Meaning

The Sanskrit word Mantra is traditionally associated with manas (मन), the mind, and tra (त्र), often interpreted in traditional explanations in relation to protection, support or liberation. Mantras occupy diverse roles across Indian traditions, including ritual, meditation, devotion and contemplation.

Depending on the tradition, the sound, pronunciation, meaning, repetition, intention and spiritual context of a Mantra can all be significant.

This is where an important distinction needs to be made.

A person repeating:

“I am confident.”

and a person Chanting:

काल हर, कष्ट हर, दुःख हर, दरिद्र हर।

सर्व रोग हर, सर्व पाप हर।

ॐ नमः पार्वती पतये।

हर हर महादेव॥

“ॐ नमः शिवाय”

are not necessarily engaging in the same practice,yet both remind us of something that modern life often forgets;What we repeatedly bring to the mind, matters and this principle appears repeatedly throughout Indian philosophical literature.

The words themselves carry a sequence of remembrance, prayer and surrender.

“कष्ट हर” — May suffering be removed.
“दुःख हर” — May sorrow be removed.
“दरिद्र हर” — May deprivation be removed.
“सर्व रोग हर” — May afflictions be removed.
“सर्व पाप हर” — May wrongdoing and its consequences be overcome.

And then:

ॐ नमः पार्वती पतये — हर हर महादेव।

The practitioner turns the mind towards Mahadev, invoking devotion, surrender and inner strength.

This is where the distinction between a modern “positive affirmation” and an Indian mantra becomes particularly interesting.

A positive affirmation may say:

“I am strong. I can overcome this. I am capable.”

A devotional mantra may instead express:

“I remember the Divine. I surrender my difficulties. Give me the strength to face them.”

The psychological experience may overlap in certain respects—repeated words can focus attention and influence what occupies the mind—but the philosophical and spiritual frameworks are different.

**The Indian tradition did not merely ask us to “think positive.”It asked us to transform the way we relate to the mind, the self, action and the Divine.**

The Bhagavad Gita: Strengthening the Mind from Within

Long before the modern language of self-help, mindset and positive thinking, the Bhagavad Gita presented a profound exploration of the human mind, fear, doubt, action, resilience, self-mastery and inner strength.

Arjuna stands before Krishna overwhelmed by confusion and despair.

Krishna does not simply tell him:

“Think positive.”

Instead, he guides him through a deeper process of understanding the self, duty, action, attachment, equanimity and mastery of the mind.

Some verses from the Gita can therefore serve as powerful sources of reflection and inner strength.

1. “Uddhared Ātmanātmānam” — Lift Yourself by Yourself

भगवद्गीता Chapter 6- Verse 6.5

उद्धरेदात्मनात्मानं नात्मानमवसादयेत्।
आत्मैव ह्यात्मनो बन्धुरात्मैव रिपुरात्मनः॥

Uddhared ātmanātmānaṁ nātmānam avasādayet
Ātmaiva hyātmano bandhur ātmaiva ripur ātmanaḥ

Meaning:
“Let a person uplift oneself by oneself and not degrade oneself. For the self alone can be one’s friend, and the self alone can be one’s enemy.”

Modern reflection:

Imagine turning this into a daily reminder:

“I will uplift myself. I will not allow my own mind to pull me down.”

This is much deeper and generates a responsibility within an individual.

2. “Ātmāiva Ripur Ātmanaḥ” — Your Mind Can Become Your Friend

The same verse gives us another profound insight:

आत्मैव ह्यात्मनो बन्धुः
आत्मैव रिपुरात्मनः॥

The self can become one’s friend or one’s enemy.

This is remarkably relevant in an age of anxiety, comparison and constant stimulation.Our circumstances matter—but so does the way we train and direct the mind,Instead of constantly saying:

“I cannot do this.”
“I am not good enough.”
“Everything is going wrong.”

“Why bad things are happening with me only” and son on……

Indian philosophy encourages us to examine the mind itself. What we are repeatedly telling our mind is very important. It reflects on our faces, words and actions.

3. “Karmanye Vādhikāraste” — Focus on Your Action

भगवद्गीता 2.47

कर्मण्येवाधिकारस्ते मा फलेषु कदाचन।
मा कर्मफलहेतुर्भूर्मा ते सङ्गोऽस्त्वकर्मणि॥

Meaning:
“You have a right to action alone, never to its fruits. Do not let the fruits of action be your motive, nor let your attachment be to inaction.”

This is one of the most widely known teachings of the BhagavadGita.

Consider its relevance to modern life.

We often tell ourselves:

“What if I fail?”
“What will people say?”
“What if I don’t get the result?”

The Gita redirects our attention:

Do your work with sincerity. Don’t let anxiety about the outcome paralyse you.

This is not merely “positive thinking.”

It is a philosophy of action and mental balance.

This is not giving up.
This is learning to let go.

4. “Samatvam Yoga Uchyate” — Equanimity Is Yoga

भगवद्गीता 2.48

योगस्थः कुरु कर्माणि सङ्गं त्यक्त्वा धनञ्जय।
सिद्ध्यसिद्ध्योः समो भूत्वा समत्वं योग उच्यते॥

Meaning:
“Established in yoga, perform your actions, abandoning attachment, and remaining even-minded in success and failure. Such equanimity is called Yoga.”

Think about the modern obsession with:

Success = I am good.
Failure = I am a failure.

Bhagavadgita Says:-

Success and failure are outcomes. They do not have to determine your inner balance.This is a powerful lesson for all of us who are navigating life with unpredictable,unimaginable circumstances and uncertainities.

5. “Nānyacintayanto Mām” — Single-Pointed Focus

भगवद्गीता 9.22

अनन्याश्चिन्तयन्तो मां ये जनाः पर्युपासते।
तेषां नित्याभियुक्तानां योगक्षेमं वहाम्यहम्॥

Meaning:
“Those who are steadfast and devoted to Me, contemplating Me without distraction, are sustained in their spiritual pursuit.”

The Gita repeatedly emphasises focused attention and steadiness.

Today we talk about:

  • mindfulness
  • focus
  • concentration
  • mental clarity
  • reducing distractions

Indian traditions have explored these questions through Dhyāna, Dharana, Japa and Yoga for centuries.

Again, these concepts should not simply be equated with modern techniques—but the conversation between them is worth having.

6. “Na Hi Kalyāṇa-kṛt Kaścit” — No Good Effort Is Lost

भगवद्गीता 6.40

न हि कल्याणकृत्कश्चिद् दुर्गतिं तात गच्छति।

Meaning:
“One who strives for what is good does not come to an unfortunate end.”

What a powerful thought for someone who feels that their efforts have been wasted.

A student who failed an examination.

An entrepreneur whose business did not work.

A person beginning again after years.

Someone learning a new skill late in life.

The message can become a personal reflection:

“My sincere effort has value. I can learn, grow and continue.”

7. “Mā Śucaḥ” — Do Not Grieve

At the conclusion of the Gita, Krishna says:

भगवद्गीता 18.66

सर्वधर्मान्परित्यज्य मामेकं शरणं व्रज।
अहं त्वा सर्वपापेभ्यो मोक्षयिष्यामि मा शुचः॥

The verse concludes with:

मा शुचः — Mā śucaḥ

“Do not grieve.”

This phrase itself carries a powerful reminder:

Do not remain imprisoned by despair.

From “Positive Affirmations” to “Sankalpa”

Another beautiful concept from Indian traditions is Sankalpa — संकल्प.

A sankalpa can refer to a firm intention, resolve or solemn determination, with its meaning varying by context and tradition.

“I will act with discipline, awareness and integrity towards my goal.”

This connects thought with action and this is an important characteristic of Indian philosophical thought:

Knowledge is not merely to be accumulated. It is to be lived.

How is this Ancient knowledge of Mantra different from the concept of Positive Affirmations?

Mantra is a diverse and sophisticated category within Indian traditions. It has already  addressed human questions in their own distinctive ways.”

That is the spirit in which Indian Knowledge Systems deserve to be studied.

Not through blind glorification.

Not through blind rejection.

But,through curiosity and research. Our ancestors through their culture and wisdom already explored:

Mantra → sound and repetition
Japa → disciplined repetition
Dhyāna → meditation
Dharana → concentration
Sankalpa → resolve/intention
Svādhyāya → self-study
Yoga → integration and discipline
Samatva → equanimity
Atma-vichara → inquiry into the self

These are not interchangeable with modern psychological terminology.

But they provide an enormous intellectual heritage that deserves to be studied rather than forgotten.

Reviving Indian Knowledge Systems does not mean rejecting everything Western,but thinking of ways to combine the Ancient Indian Knowledge with the modern Education System and make it more effective and practical.

It means developing the confidence to say:

“Let us learn from everywhere—and also remember to learn from our own roots.”

A civilisation does not become modern by forgetting its past.

It becomes stronger when it can carry its wisdom forward while engaging critically with the present.

**Our roots are not outdated.

Perhaps we simply stopped looking at them.**

And maybe the next generation should not have to rediscover its own heritage through someone else’s vocabulary.

I think that the real journey is not from ancient to modern,Perhaps it is from forgotten to rediscovered.

Let us explore our Indian Knowledge Systems.
Let us question. Let us research. Let us understand.

The real task is to remember the wisdom behind our own words.

And above all—let us pass the knowledge forward.

हरे कृष्ण हरे कृष्ण | कृष्ण कृष्ण हरे हरे |
हरे राम हरे राम | राम राम हरे हरे | 🙏

हर हर महादेव। 🙏

When Three Chokepoints Fail Together: Rethinking Maritime Resilience After 2026

By: Khushbu Ahlawat, Consulting Editor, GSDN

Maritime Resilience: Source Internet

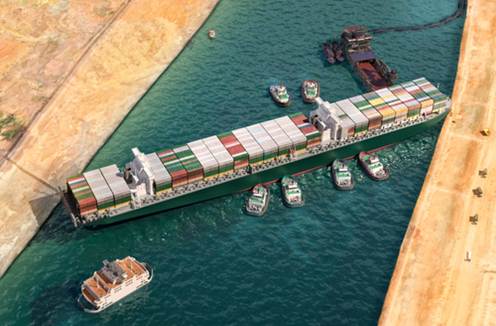
For most of the past decade, the story of global shipping’s vulnerable chokepoints has been a story told one crisis at a time. The Red Sea crisis of 2023-24 forced container lines around the Cape of Good Hope. The Panama Canal drought of the same period cut daily transits by more than half. The two overlapped briefly but were, in essence, separate emergencies with separate causes — one geopolitical, one hydrological — and each eventually eased on its own schedule. That pattern is why so much of the policy literature on maritime resilience, useful as it is, still tends to treat chokepoint disruption as something that happens to one artery of world trade at a time, testing a single alternative route before the system returns to something like normal.

The 2026 has broken that pattern. As of this September, the Strait of Hormuz has been effectively contested for close to seven months, following the US and Israeli strikes on Iran that began on 27-28 February and Iran’s subsequent missile, drone and small-boat campaign against tankers transiting the strait — a low-intensity war that the US House of Representatives has now voted three separate times to try to end, without success, and that the International Maritime Organization says has already killed seafarers aboard attacked vessels. At almost exactly the same moment, the Houthis in Yemen — who had suspended their attacks on Red Sea shipping after the October 2025 Gaza ceasefire — resumed strikes against Israel in March 2026 as part of the wider Iran war, extended their targeting to Saudi Arabia in July, and by September were fighting renewed clashes with Yemeni government forces even as the broader regional conflict continued. And the Panama Canal, which had spent all of 2025 recovering from its own drought and reached near-record water levels by February 2026, found itself cutting daily transits again by September as a returning El Niño pattern dried out the watershed feeding Gatún Lake for a second time in three years.

That is not three separate emergencies. It is three of the world’s most consequential maritime corridors under simultaneous or overlapping stress, in the same calendar year, for reasons that range from open warfare to weather. It is worth asking whether the resilience toolkit that emerged from the 2023-24 experience — better digital coordination, targeted infrastructure spending, corridor-level contingency plans — is actually built for a year like this one, or whether it was designed for a world where chokepoints fail politely, one at a time.

What the numbers actually show

The scale of the Hormuz disruption alone justifies treating it differently from the Red Sea and Panama episodes that preceded it. Around 20 million barrels a day of oil and petroleum products, close to a fifth of the world’s petroleum liquids, normally transits the strait; in the opening weeks of the crisis, transits collapsed as insurers withdrew war-risk coverage and shipowners judged the route too dangerous regardless of what naval escorts might promise. Brent crude, which had been trading near $71 a barrel just before the US and Israeli strikes began, spiked above $114 within two weeks and has swung violently ever since — plunging by nearly 9 percent in a single session in March on reports that Washington was considering direct military action to reopen the strait, then climbing again as Iranian forces declared it “closed” and the US moved to blockade Iran’s own remaining exports in April. Seven months on, the strait is neither fully open nor fully closed; it sits in the kind of prolonged, contested state that is arguably harder for shippers, insurers and importing governments to plan around than a clean closure would be, because every week brings a fresh judgment call about whether the risk premium justifies the voyage.

The Panama Canal’s second act of the decade is smaller in absolute terms — the Canal Authority’s cut from 36 to 34 daily transit slots this September is nowhere near the collapse to 18 vessels a day seen at the depth of the 2023-24 drought — but it matters precisely because of the timing. Roughly 3.2 million barrels a day of crude, condensate and petroleum products, plus some 600 million cubic feet of LNG daily, were moving through the canal as of the second quarter of 2026, much of it US Gulf Coast supply heading to Asian buyers who might otherwise have looked to the Pacific route as a Hormuz-era alternative. A canal that is simultaneously trying to absorb rerouted traffic from a Middle East crisis and rationing its own transit slots because of drought is not the reliable release valve that resilience planning assumes it will be.

The Red Sea, for its part, never fully recovered from its first disruption before being hit by its second. Traffic through Suez had only partially rebuilt when the Houthis, whose late-2025 pause had briefly allowed some shipping lines to test a cautious return to the route, resumed attacks in March 2026 as the Iran war widened. For a shipping industry that had spent 2025 gradually recalibrating its risk models around a Red Sea that was becoming safer, the resumption in 2026 was a reminder that these disruptions do not necessarily end — they pause, sometimes for the better part of a year, before the underlying conflict re-erupts on a fresh trigger.

Why the standard resilience prescriptions are necessary but not sufficient

The case for digital trade facilitation and targeted infrastructure investment, which has become the standard policy response to chokepoint vulnerability, is genuine and evidence-based. Countries with fully implemented Maritime Single Windows and Port Community Systems do show meaningfully higher liner shipping connectivity scores than those without, and UNCTAD’s own modelling suggests that lifting transport-sector investment from the bottom quintile of spending levels toward the middle of the distribution could cut maritime transport costs by high single digits. None of that is in dispute, and it is exactly the kind of unglamorous, compounding investment that pays off over a decade.

But 2026 has exposed the limit of what these tools can do against the specific shocks that actually happened this year. A Maritime Single Window speeds the paperwork around a port call; it does nothing to restore war-risk insurance once underwriters have priced a strait as uninsurable, which is the actual mechanism by which Hormuz transits collapsed by more than 90 percent in the early weeks of the crisis — the ships were physically able to sail, but nobody would underwrite them, and no amount of digital customs coordination changes an insurer’s risk appetite. Port Community Systems improve coordination and cargo visibility at the terminal; they do not add a drop of water to Gatún Lake when El Niño suppresses rainfall across the Panama watershed, nor do they change the physical draft restriction that follows from a lower reservoir. These are real limitations, not arguments against digitalisation, but they suggest that a resilience strategy built primarily around digital coordination and general infrastructure spending is optimised for reducing friction in a functioning system, not for the specific failure modes — war-risk insurance withdrawal, hydrological scarcity, prolonged low-intensity conflict — that have actually driven this year’s disruptions.

What 2026 argues for instead is resilience investment aimed more precisely at those failure modes: sovereign or regional war-risk insurance pools that can keep essential cargo — food, fertiliser, medical supplies — moving through contested waters when commercial underwriters withdraw, the way several Gulf-dependent economies have had to improvise on an ad hoc basis this year; strategic petroleum and fertiliser reserves sized against months rather than weeks of disruption, given that the Hormuz crisis has now outlasted most countries’ typical buffer-stock assumptions; and diversified routing agreements negotiated before a crisis rather than during one, so that a Panama Canal capacity cut does not collide with a Hormuz-driven demand surge for exactly the same alternative route.

The compounding cost for the countries least able to absorb it

The distributional picture that concerns organisations like UNCTAD has not improved this year; if anything, the simultaneity of 2026’s disruptions has sharpened it. Small island developing states, whose liner shipping connectivity already runs at a fraction of larger economies’ and which have far fewer alternative routes to switch toward when one closes, are being asked to absorb the effects of overlapping shocks rather than sequential ones. Landlocked developing countries, already paying transit costs some 85 percent above the global average because they depend on transit through neighbouring states, have even less room to reroute around a contested strait or a rationed canal. And economies that rely heavily on Gulf-origin fertiliser shipments — Sudan, Tanzania, Somalia and Kenya prominent among them — are exposed to a natural-gas price channel that has moved sharply this year: Dutch TTF gas prices, which are a reasonable proxy for the ammonia and urea costs that flow into nitrogenous fertiliser, spiked amid the Hormuz disruption in ways that will show up in planting-season input costs for farmers who have no say in any of the geopolitics driving the price.

Layered on top of this is a sovereign-debt picture that had already deteriorated before 2026’s disruptions began. Developing-country interest payments rose far faster than revenues over the decade to 2024, and a large share of least-developed and small island states were already spending more on debt service than on health or education. External borrowing costs for African and developing Asian sovereigns spiked further after the Hormuz war began, precisely when many of these same governments needed fiscal room to cushion higher food and fuel import bills. That combination — a compounding trio of maritime shocks landing on economies with the least fiscal space to absorb them — is the real policy problem 2026 has surfaced, and it is one that digital trade platforms and general infrastructure spending, however useful, were not designed to solve on their own.

What resilience should mean going forward

None of this argues against the recommendations that emerge from the UNCTAD-style analysis of these events — completing digital trade platforms, integrating chokepoint monitoring into contingency planning, and targeting infrastructure spending at demonstrated bottlenecks all remain sound, necessary steps. But a year in which a war-driven closure, a resumed insurgent campaign and a weather-driven capacity cut have overlapped across three different chokepoints argues for adding a further layer: contingency planning that assumes simultaneous, not sequential, disruption, insurance and reserve mechanisms built for shocks measured in months rather than weeks, and — for the most exposed developing economies — dedicated international financing that treats chokepoint disruption as a recurring fiscal risk to be pre-funded, not a one-off emergency to be responded to after the fact.

There is also a planning assumption worth retiring outright: that the world’s major shipping corridors are independent risks that can be modelled separately and added together. The Panama Canal’s drought exposure and the Strait of Hormuz’s geopolitical exposure have no obvious causal link, yet both landed on global energy shipping in the same window this year, and a Red Sea route that shippers had begun cautiously trusting again was pulled back into the same conflict that closed the strait. Corridors that look statistically independent on paper can become correlated in practice the moment a single regional war widens far enough to touch two of them at once, which is exactly what happened between February and September 2026. Contingency planning built on the assumption of independent chokepoint risk will systematically understate how bad a bad year can get; planning built on the assumption that a serious regional conflict can plausibly touch two or three corridors simultaneously would have been far closer to what actually happened this year, and it is the more realistic baseline for the next one.

The 2023-24 disruptions taught the shipping industry and its regulators a great deal about rerouting around a single blocked corridor. 2026 has taught a harder lesson: that the corridors themselves cannot always be counted on to fail one at a time, and that the next resilience strategy needs to be built for the year that just happened rather than the one that came before it.

Before the Barrels Move: What Canada’s Pacific Pivot Actually Requires of India

By: Khushbu Ahlawat, Consulting Editor, GSDN

Canada’s Specific Pivot: Source Internet

The commercial logic for India to buy more Canadian oil and gas is easy to state and, on its face, hard to argue with. Russia supplied roughly 39 percent of India’s crude-import bill in 2025-26, a concentration that would worry any energy planner even without the added complication that Washington is now actively legislating against it. Add a more volatile West Asia, and a Pacific-coast alternative that is neither Russian nor Gulf-origin looks like an obviously sensible hedge. But the gap between “sensible hedge” and “functioning supply relationship” is wider than the commercial case alone suggests, and it is worth walking through why, because the answer says as much about politics and shipping logistics as it does about barrels and price.

A door that was shut two years ago

The most important fact missing from any purely commercial reading of the Canada-India energy opportunity is how recently, and how completely, the political relationship underpinning it was broken. In September 2023, then-Prime Minister Justin Trudeau told Canada’s parliament there were “credible allegations” linking agents of the Indian government to the killing of Sikh separatist Hardeep Singh Nijjar in British Columbia. India called the charge absurd; both countries expelled diplomats through 2024, New Delhi suspended visa services for Canadians, and trade talks that had been progressing toward a bilateral trade agreement went into a deep freeze that lasted the better part of two years.

The thaw is real, but it is young. Mark Carney’s election as Canadian prime minister in May 2025 created the political space for a reset that neither side had been willing to attempt under Trudeau; Carney and Narendra Modi met at the G7 summit in Kananaskis in June 2025, agreed to restore full diplomatic representation, and by February-March 2026 Carney was in New Delhi signing eight agreements spanning trade, energy, agriculture and space, alongside a push to fast-track a Comprehensive Economic Partnership Agreement targeting $50 billion in bilateral trade by 2030. Canadian officials have said they believe Indian government-linked interference activity in Canada is “not continuing,” which is itself a significant, if carefully hedged, statement. But the underlying dispute has not disappeared — the World Sikh Organization said as recently as this year that a prominent Canada-based activist and his family had been warned by police of threats it attributed to Indian government agents, and four Indian nationals remain before Canadian courts on charges related to the Nijjar killing. Analysts who have tracked the relationship closely describe the current state as “a meaningful thaw, moving in the right direction, but not a clean slate.”

This matters for the energy conversation specifically because long-term crude and LNG off-take agreements — the kind of multi-year commercial architecture that would actually move Canadian barrels into India’s refining system at scale — are not the sort of commitment either government’s companies sign lightly against a backdrop that a single diplomatic incident could reopen. The commercial case for diversification away from Russian and Gulf supply has existed for years. What has changed only in the past eighteen months is that the political container for building it has reopened at all.

Why the barrels aren’t already moving

Even with the politics stabilising, the physical and commercial mechanics of getting Canadian crude to India remain genuinely difficult in ways that go beyond the simple fact of distance. The Trans Mountain Expansion, operating since May 2024, loads its Pacific-bound crude at the Westridge terminal in Burnaby, where Burrard Inlet’s draft restrictions mean that even Aframax-class tankers — the largest vessels the terminal can handle — typically load only around 96,000 of their roughly 120,000-tonne capacity, well short of the size that makes a long-haul voyage to Asia economical. For a nearby buyer like China or a US Gulf Coast refiner, that is a manageable constraint. For a shipment all the way to an Indian refinery, it usually is not: the more cost-efficient method is to sail the partially loaded Aframax down to a ship-to-ship transfer zone off the Mexican Pacific coast and top up a much larger Very Large Crude Carrier there before the long Pacific and Indian Ocean crossing — an operation that shipping analysts estimate adds several dollars a barrel in lightering costs on top of the pipeline’s own roughly $11-a-barrel tariff from Alberta to the coast. None of this is prohibitive at scale, and it is exactly the kind of cost that long-term contracts and dedicated shipping arrangements can absorb more efficiently than one-off spot cargoes. But it explains, in very concrete terms, why “Canadian crude to India” so far means occasional cargoes rather than a standing trade lane, and why China — closer, with more established lightering logistics already built around its own volumes — has been able to import roughly three times as much Canadian crude as India despite both countries discovering the Pacific route at roughly the same moment.

There is also a first-mover problem that goes beyond logistics. Chinese refiners moved quickly once TMX opened, and by 2025 were taking nearly a third of everything shipped out of British Columbia to non-US destinations. Those relationships — refinery-specific crude assays, established trading desks, existing lightering arrangements — are the kind of infrastructure that compounds over time; each additional cargo makes the next one cheaper and easier to arrange. India’s Reliance and Indian Oil have already bought Canadian heavy grades for Jamnagar and other refineries capable of processing Western Canadian Select’s sour, heavy characteristics, which is a genuine technical advantage India holds over some competing buyers. But turning a capability into a habitual trade flow requires exactly the kind of longer-term commercial commitment that the diplomatic freeze delayed India from pursuing at the same pace China did.

The sanctions clock

The case for urgency is not hypothetical. In late July 2026 the US Senate voted 86-11 to advance the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 — renamed after Senator Graham’s death, and now covering both Russia and, at President Trump’s request, Iran. The bill as passed by the Senate has been scaled back from an earlier proposal to impose a blanket 500 percent tariff on any country doing business with Russia’s energy sector; as advanced, it would instead authorise tariffs of up to 100 percent specifically on the top handful of importers of Russian oil and gas, a list that currently includes India, China, Azerbaijan, Hungary and Slovakia, alongside a presidential waiver that gives the White House discretion over whether and when to actually impose it. The bill still needs to clear the House of Representatives, which reconvened at the end of August, before it becomes law, and Indian officials have already raised concerns that penalising India while several European buyers of Russian gas escape equivalent treatment amounts to a double standard. It would be premature, as the case for Canadian diversification itself acknowledges, to redesign Indian energy policy around a bill that has not passed. It would be equally imprudent for Indian refiners to assume the current arrangement — Russian crude accounting for more than half of India’s imports in some recent months, according to trade data — can simply continue unexamined while that legislation sits one procedural step from the president’s desk.

LNG and uranium: the longer game

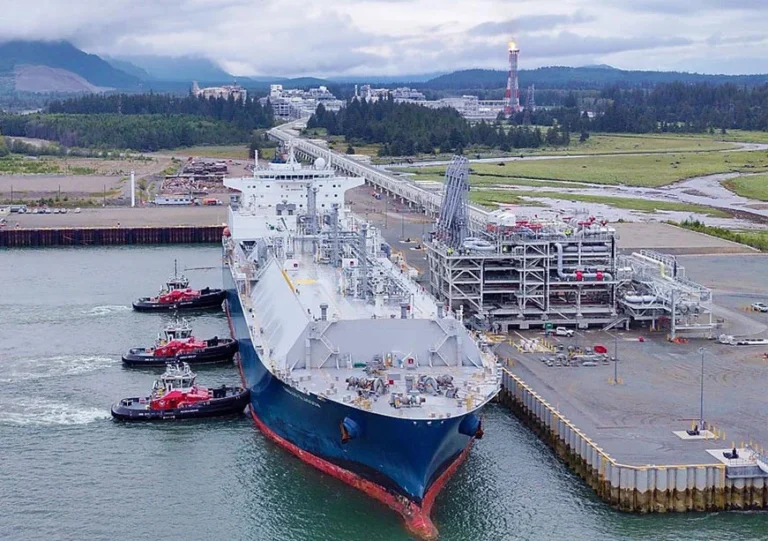
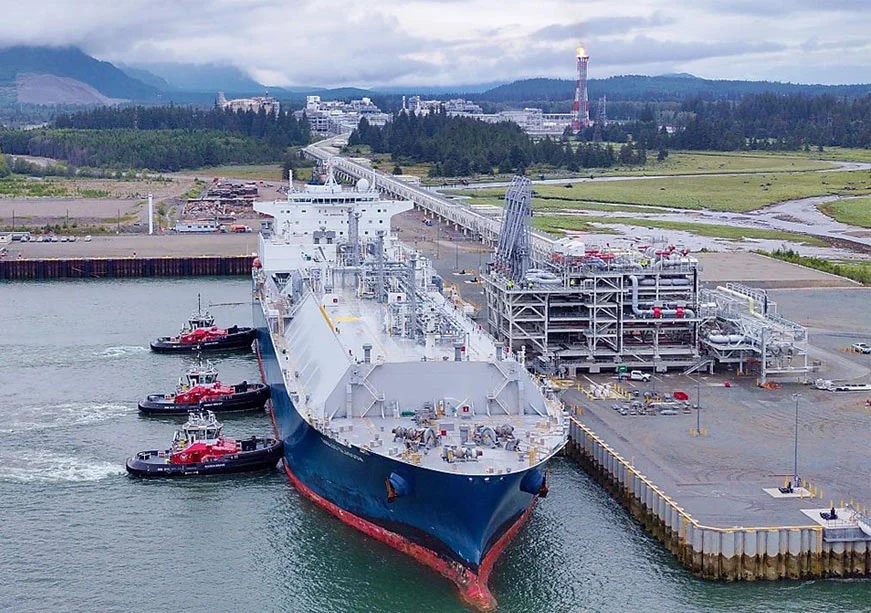
If crude oil diversification is a near-term hedge, Canadian LNG is closer to a decade-long infrastructure bet. LNG Canada’s Kitimat facility only began shipping in the past two years, giving Western Canadian gas its first serious Pacific export route; Ottawa’s targets of 50 million tonnes of annual LNG capacity by 2030, rising to 100 million by 2040, are ambitious relative to where the industry stands today, and Canadian volumes will have to compete on price and reliability against Qatar, the United States and Australia, all of which sit closer to India or have more mature supply relationships already. The India-Canada Strategic Energy Partnership announced this year gives the two governments a framework to work from, but a framework is not a contract, and turning it into one will likely take longer than the crude story precisely because Canadian LNG export capacity is still being built rather than already flowing.

The one part of this relationship that has moved with more institutional weight is civil nuclear cooperation. India and Canada have advanced toward a long-term uranium supply arrangement even as the broader relationship was being rebuilt, and it sits alongside India’s own 2025 legislative push — the SHANTI Bill, aimed at accelerating domestic nuclear capacity toward a stated goal of 100 gigawatts by 2047 — giving the uranium relationship a domestic Indian policy driver independent of the oil-and-gas diversification argument. That combination, a recovering bilateral relationship plus a genuine domestic Indian demand signal, may end up making uranium the most durable strand of the emerging Canada-India energy relationship, even if it attracts less attention than tanker cargoes of heavy crude.

What actually needs to happen next

None of this is an argument against pursuing the Canadian option; if anything, the specific obstacles point toward what would need to happen for the relationship to move from occasional cargoes to a real trade lane. On the commercial side, that means exactly what off-take negotiations are meant to solve: multi-year contracts that let shipping and lightering arrangements be planned around predictable volumes rather than spot-market opportunism, and that make Indian equity participation in Canadian production or export infrastructure a realistic proposition rather than a talking point. On the infrastructure side, it means Canadian federal and provincial governments actually resolving the Burrard Inlet dredging question that currently caps how much crude even a fully committed Aframax can carry out of Vancouver — a domestic Canadian political and environmental debate that will shape Indian import economics as much as anything New Delhi does. And on the political side, it means both governments continuing to manage a relationship that is stabilising but not yet fully repaired, with enough care that a future diplomatic flashpoint does not once again freeze exactly the kind of long-term commercial commitments this opportunity depends on.

The comparison that matters more than price

It is worth being precise about what kind of diversification this actually is, because the temptation in energy-security writing is to treat every new supplier as interchangeable insurance against every existing risk. Canadian crude does not solve the same problem that a Gulf disruption creates. Russian barrels are priced at a discount that exists specifically because sanctions risk has driven other buyers away; Canadian barrels carry no such discount; and Gulf supply, whatever its political volatility, still benefits from short transit times and an already-built tanker and refining ecosystem that decades of Indian imports have optimised around. What Canada offers is not a cheaper or faster alternative to either. It is a third pole of supply that happens to sit outside both the sanctions architecture threatening Russian barrels and the maritime chokepoints — the Strait of Hormuz above all — that periodically make Gulf supply expensive to insure and risky to route. That is a genuinely different kind of value, but it is a slower and more expensive one to build, which is precisely why it needs to be built during a calm period rather than assembled in a hurry once a crisis has already narrowed India’s options.

The historical pattern in Indian energy diversification is instructive here. India’s pivot toward discounted Russian crude after 2022 happened remarkably quickly, but only because the commercial incentive — a steep price discount — was large enough to override the usual frictions of building new supplier relationships from scratch. Canada offers no equivalent price signal; its crude sells close to global benchmarks once shipping costs are included, and its LNG will have to compete on delivered cost against suppliers with a decade’s head start into the Indian market. That means the Canada relationship will not build itself the way the Russia relationship effectively did. It will only be built if Indian refiners, Canadian producers and both governments treat the current diplomatic opening as a limited window for doing the unglamorous work — contracts, equity stakes, dredging permits, shipping arrangements — that a price-driven pivot never required. The barrels can move. The question is whether the politics, the shipping economics, and the negotiating timelines can all move together before either a Russian sanctions bill or the next diplomatic crisis forces India’s hand on a timeline it did not choose.

Ground Broken, Not Yet Built: What Koizumi’s Visit Really Shows About India-Japan Defence Ties

By: Khushbu Ahlawat, Consulting Editor, GSDN

India- Japan Defence Ties: Source Internet

Shinjiro Koizumi’s two-day visit to India in August 2026 has been read, reasonably, as a turning point. A decade of dialogues, exercises and framework agreements between New Delhi and Tokyo finally produced something with teeth: a Memorandum of Arrangement on Maritime Security Cooperation, fresh commitments on shipbuilding and ship-repair, and a review of the one hardware project — the UNICORN naval antenna system — that both governments now point to as proof the relationship has moved from words to weapons. Set against the diplomatic and military architecture the two countries have spent more than ten years assembling, this looks like momentum.

Set against a different timeline, though, the same visit raises a harder question. Four months before Koizumi arrived in New Delhi, Japan did something it had not done in eighty years: on 21 April 2026, Prime Minister Sanae Takaichi’s government formally lifted the postwar ban on Japanese arms exports altogether, scrapping the last restrictions that had confined defence transfers to five non-lethal categories — rescue, transport, warning, surveillance and minesweeping — and opening the door, for the first time since 1945, to Japanese-made weapons systems being sold abroad. That is one of the most consequential shifts in Japanese security policy since Shinzo Abe first cracked open the arms-export ban in 2014. It is also a shift that, on paper, should have made this exact moment — a defence-ministerial visit to Tokyo’s most important Indo-Pacific security partner outside the US alliance system — the obvious occasion to announce something bigger than an antenna.

That it did not is worth taking seriously, because it says more about the real state of India-Japan defence cooperation than the framework agreements do.

A decade of loosening that has mostly bypassed India

Japan’s arms-export liberalisation has proceeded in visible stages, and each stage has had an obvious first beneficiary — and it has rarely been India. Abe’s 2014 reform opened the door to exports in principle; the first country to walk through it was the Philippines, which signed a contract in November 2023 for Japanese air-surveillance radar, becoming the first foreign recipient of Japanese-built defence equipment since the Second World War. Tokyo followed that with the transfer of retired patrol vessels to Manila and, in 2023, approval for the re-export of US-made Patriot missile interceptors back to the United States. In December 2025, the ruling coalition agreed to remove the five-category ceiling entirely for exports tied to the Global Combat Air Programme, the next-generation fighter jet Japan is co-developing with the UK and Italy, clearing the way for that aircraft to be sold to third countries. Then came April 2026’s wholesale removal of the ban.

India’s own defence-technology relationship with Japan, by contrast, has moved at a noticeably slower pace despite starting from a stronger position on paper. The 2015 bilateral agreement on transfer of defence equipment and technology predates the Philippines deal by eight years. Yet for most of the decade that followed, the flagship candidate for an actual transfer — the ShinMaywa US-2 amphibious search-and-rescue aircraft — was discussed, costed and re-costed without ever being signed, before quietly falling off the agenda. It was only in November 2024 that the two governments signed a Memorandum of Implementation for what is now the relationship’s one concrete hardware project: co-development of the UNICORN integrated mast, a stealth communications antenna already fitted to Japan’s Mogami-class frigates, to be adapted for Indian Navy ships by Bharat Electronics Limited. Even that milestone came with an asterisk — Japan’s own trade press has noted that India became only the second Asian country, after the Philippines, to receive any Japanese defence technology, a decade after the two sides signed their framework agreement and nearly a decade after Tokyo had already delivered hardware to a partner with a far smaller defence-industrial base and a much shorter strategic relationship with Japan.

Koizumi’s August 2026 visit added an actual signing to that picture — the Maritime Security Cooperation MoA — plus a commitment to “explore” joint naval shipbuilding and design, and to “examine” reciprocal ship-repair arrangements. Those are, in the vocabulary of defence diplomacy, first-stage verbs. They describe intentions to negotiate, not contracts to build.

Why India, despite the head start, keeps taking longer

Part of the answer is structural, and has little to do with either government’s enthusiasm. India’s defence procurement system is built around import substitution rather than straightforward purchase: any Japanese offer has to be routed through “Make in India” localisation requirements, indigenous-content thresholds and, increasingly, a preference for co-development over co-production, let alone outright import. That is precisely the model the UNICORN project follows — Bharat Electronics leading integration and manufacturing in India rather than simply installing an imported Japanese system — and it is a more defensible long-term industrial strategy than a straight purchase. But it is also slower, because it requires two defence bureaucracies to agree not just on price and specification but on technology-sharing terms, intellectual-property arrangements and local production standards, all before a single unit is built. The Philippines’ 2023 radar deal, by contrast, was a conventional government-to-government sale — Manila bought a finished Japanese system outright, which is why it could be signed within a few years of Japan’s 2014 reform while India’s more ambitious co-development model has taken until 2026 to produce its first project.

There is also a queue problem. India’s most consequential recent defence-industrial breakthroughs — the agreement to co-produce GE Aerospace F414 jet engines domestically, the deepening submarine and Rafale-linked cooperation with France, the continuing dependence on Russian-origin platforms and spares across large parts of the armed forces — all predate or run parallel to the Japan relationship, and each of those partners has been willing to move faster on transferring sensitive technology than Tokyo historically has been. Japan arrives at India’s door as one claimant among several on a limited pool of procurement bandwidth and political attention, competing against relationships that are older, deeper, or backed by more aggressive commercial terms. The 2015 framework agreement gave Japan an early seat at that table; it did not guarantee Tokyo would move up the queue.

Finally, there is Japan’s own domestic caution, only partly addressed by April’s reform. Even after the ban was lifted, the revised rules still route lethal weapons exports through a list of seventeen countries with which Japan has concluded defence equipment transfer agreements, and continue to bar transfers to states engaged in active conflict except in exceptional circumstances. Japanese firms — many of which built their post-war business models around never selling into a war zone or exporting anything that could kill — have also been slow to reorient production and marketing toward exports even where the legal barriers have fallen; SIPRI data cited in Japanese trade coverage shows major contractors’ arms-related revenue rising sharply in 2024, but from a small base, and mostly on the back of expanded domestic procurement rather than new export contracts. The legal architecture for a much bigger India-Japan hardware relationship now exists. Whether Japanese industry, or the Indian procurement system, is ready to use it at speed is a separate question.

What the maritime pact actually locks in

None of this is a case against what Koizumi’s visit did achieve. The Maritime Security Cooperation MoA is a meaningful step precisely because it addresses a genuinely under-built part of the relationship: shared maritime-domain awareness between two navies that sit at opposite ends of the Indo-Pacific’s main sea lanes, with the Indian Navy anchoring the western Indian Ocean and the Japan Maritime Self-Defense Force focused on the East China Sea and the waters around Taiwan. Better information-sharing between those two theatres, plus the logistics arrangements — port access, mutual repair facilities — that the agreement points toward, would genuinely extend both navies’ operational reach in a way that joint statements alone never could. Koizumi’s stop at India’s Western Naval Command in Mumbai before travelling to New Delhi, a part of the country’s maritime geography that Japanese defence visits have historically paid less attention to than the Bay of Bengal, is a small but real sign that Tokyo is thinking about the relationship in genuinely Indian Ocean-wide terms rather than only through the lens of its own immediate neighbourhood.

Koizumi himself, on his first visit to India as defence minister, was notably candid about this gap between aspiration and delivery, telling his hosts that the defence relationship had “yet to reach its full potential” even as the two sides signed a wide-ranging joint statement — an unusually direct admission, for a diplomatic visit, of exactly the pattern this piece has traced. The exercises are also becoming more ambitious in their own right: Japanese fighter aircraft joined the Veer Guardian drill in India for the first time this September, and the two sides have agreed to raise the complexity of future exercises, integrate unmanned systems, and open a dialogue between special-operations forces and India’s emerging integrated theatre commands.

The honest reading of the Koizumi visit, then, is not that India and Japan have failed to build a serious defence relationship, but that they have built two different things at two different speeds. The institutional and operational layer — dialogues, exercises, information-sharing, logistics access — has genuinely matured, and the new maritime pact extends it further. The hardware layer, the one that actually determines whether either navy’s capability changes because of the other’s technology, has been unlocked by Japan’s legal reforms far more than it has been built by either country’s procurement system. Japan removed its postwar arms-export ban in April; it did not thereby remove India’s localisation requirements, its competing supplier relationships, or the multi-year negotiation cycle that even the smaller, single-item UNICORN project needed to move from a 2015 framework to a signed 2024 implementation memorandum. The next real test of this relationship is not whether Tokyo is willing to sell — after April 2026, it plainly is — but whether New Delhi’s own defence-industrial machinery can move fast enough to take what is now, for the first time since the Second World War, actually on offer.

What would actually close the gap

Three things would tell us, over the next year or two, whether the hardware layer is catching up with the institutional one rather than simply being announced faster than it is delivered.

The first is the shipbuilding conversation the two defence ministries agreed to “explore.” Japan’s shipbuilders bring genuine, differentiated expertise — hull design, propulsion and stealth-signature reduction of the kind embodied in the Mogami-class frigate programme — that neither France nor Russia, India’s two largest current naval-technology partners, offer in quite the same form. But exploratory talks on joint design and reciprocal ship-repair facilities are a long way from a construction contract, and Japan’s own shipbuilding industry has limited spare capacity: Tokyo is simultaneously trying to expand naval output for its own fleet, support the Mogami-class export pitch to Australia and other partners, and now potentially service GCAP-related production, all with a shipbuilding workforce that has been shrinking for decades. Whether Japan can prioritise Indian yards over its own domestic orders, and whether India’s Make-in-India conditions can be reconciled with Japan’s traditionally tight control over hull and propulsion technology, will determine whether this becomes the relationship’s second hardware project or its second decade-long conversation.

The second is what happens to the Indigenous Integrated Mast programme that Bharat Electronics had already begun developing with the Indian Navy before UNICORN arrived. Naval-industry reporting has suggested the two projects may need to be merged or reconciled rather than run in parallel, and how that plays out will be an early signal of whether Indian and Japanese engineering teams can actually collaborate on a shared technical roadmap, or whether UNICORN ends up layered awkwardly on top of an existing indigenous effort rather than genuinely integrated with it.

The third, less visible but arguably more important, marker is procedural: whether the fourth 2+2 Foreign and Defence Ministerial Meeting, which both sides have now agreed to accelerate toward Tokyo, produces a second signed hardware project rather than another set of framework commitments. A single co-development agreement, however genuine, is a proof of concept. A second one, agreed on a shorter timeline than the nine years UNICORN took from framework to implementation, would be the first real evidence that Japan’s April 2026 policy shift is translating into an Indian defence-industrial pipeline rather than sitting, for now, as an open door that New Delhi has yet to fully walk through.

None of this diminishes what Koizumi’s visit achieved on the maritime and operational side, where the relationship’s progress looks considerably more solid than on the hardware side. But conflating the two — treating a maritime-domain-awareness pact and an antenna project as evidence that India-Japan defence cooperation has crossed some general threshold from institutional to operational — risks overstating how far the hardware relationship has actually moved relative to what Japan’s own policy reforms now make possible. The two governments have, in a real sense, finally built the legal and diplomatic scaffolding for a much larger defence-industrial partnership. Whether they build anything more inside that scaffolding than one stealth antenna is still an open question, and it is one that neither an MoA nor a joint statement can answer.

Why China’s Grip on Rare Earth is Ringing Warning Bells for the World 

By : Soumya Dutta, Research Analyst, GSDN

China’s Grip on Rare Earth : Source Internet

Indonesia, the country with the world’s largest nickel reserve at approximately 60% had decided to halt its export in 2020. Jakarta wanted to control its domestic production, attract investment, and add itself to the value chain of the global EV and clean energy market. For a while this worked, with its economy making a fivefold jump between 2013 and 2022, but this push towards resource nationalism came at the expense of foreign investments controlling its downstream production process, a large part of which is now dominated by China. Therefore, while Indonesia successfully turned its nickel resources into riches, a large part of its operational output is still generated with reliance over foreign capital and technology, which is in contrast with how China has managed its control over rare earth materials. Beijing has not just found its control of critical minerals economically viable, but its approach includes supply-chain management, which mean China not only extracts, it processes and refines and it is this end-to-end management with a tight grip on its exports that has generated considerable anxiousness in the world. 

An overview of the industry now operating in China shows the underlying process, beginning from the extraction of rare earth elements (REE) which is concentrated in two large belts: the region of Baotou in Inner Mongolia and the other in Ganzhou located at the Jiangxi Province and is largely operated through a government duopoly which are the China Northern Rare Earth Group working in the Bayan Obo mining district of the Baotou region as well as China Rare Earth Group (or more commonly China Southern) in a couple of regions down south, including Jiangxi, Hunan, Guangdong, with both of these companies being a descendant of the ‘Big Six’, a major conglomerate in China that dominated this critical sector. According to the International Energy Agency (IEA), its 2024 report showed that China accounts for nearly 60 per cent of the total REE production and the refinement accounting for 91 per cent of the total output. Banking on this advanced production process Beijing’s approach has allowed it to actually connect and strengthen its domestic supply chain visible from its 94 percent share of permanent magnets and fueling the broader ecosystem by supplying EVs such as the BYD automobile group, wind turbines manufacturers such as Goldwind and drone companies such as DJI who are reliant on the REE and subsequently absorb them rather than procuring it and connecting to foreign competitors. This gives Beijing the ability to set down the agenda and leverage its position in a way best explained by Deng Xioaping remarks in 1992, “The Middle East has oil. China has rare earths.” allowing it to further dabble in chokepoint politics of intentional delays and interruptions that reverberate throughout the supply lines. 

A recent occurrence has been the halt in REE exports to US, which comes ahead of Xi Jinping’s high stakes visit to Washington in the end of September, which will also shape the trajectory of the Busan agreement that both the countries had reached in October 2025 over relaxing export restrictions. By using its edge China has repeatedly banned the extraction and separation of these critical elements, while simultaneously restricting its intellectual know-how making it difficult to close the capability gap between Beijing and other nations. There is a total of 17 elements found in China and according to two successive notifications released the catalogue now includes 12 elements which are now restricted including both medium and heavy elements such as scandium, yttrium, samarium and terbium. The ‘Busan truce’, then seen as a move towards easing policy relations, therefore had quite a troubled longevity. Succeeding the ‘Busan truce’, a future ‘Washington truce’ may pave the way with exchanges between Trump-Xi at the end of this month, providing relief not only to the US but to those who are equally reliant on these critical elements. But despite diplomatic signaling and rapprochement China remains by far the largest possessor and manufacturer with an entire industrial ecosystem built around it, and with the ability to cut off the flow anytime an uneasiness has continued to remain with REE as a strain in relations for those dependent on it. 

Why does China dominate? 

At the juncture, an inquisition of why China continues to dominate despite the countries’ growing apprehensions about it, is rooted in the contradiction of globalization. This approach has created an ecosystem that is interconnected and interdependent, therefore breaking away and creating a value chain outside the current dominant structure will result in significant incurring of cost and a political vision that must compete against time itself. Experts argue that the process will take a decade if not more, to reproduce what China has achieved incrementally since the 1990s and to do this, the process will need two major grounds: absorbing the environmental costs that the Ministry of Industry and Information Technology in China had highlighted in 2011 to be estimated at ¥38 billion (or $5.6 billion) and sharpening the midstream and downstream capacity which means building both infrastructure and human capital skilled in this sector. 

So for countries who has embedded themselves in the phenomenon of globalization must ask how far they are willing to go to reduce this dependence that has built up over the years through the 3Ds of de-risking (stockpiling the essential REE and to ensure that the countries are able to absorb the shock); diversification (how well are the US, EU, India, Australia, Japan willing to cooperate to have a ‘China +1’ strategy at a time when they are equally worried about a single country dominating the chain) and decoupling (creating a supply chain within the boundaries of its own geography, which will be difficult to execute as market rationality and national security pull each other from the opposite sides). 

The Way Forward 

Moving forward, rather than relying on a single approach, countries are applying a mix of strategies that is de-risking, diversifying and building indigenous capabilities, although not outright decoupling. The primary focus has therefore been self- development through stockpiling efforts as reflected in strategies from the US ‘National Defense Stockpile: Actions Needed to Improve DOD’s Efforts to Prepare for Emergencies’ as well as the EU ‘Critical Raw Materials Act’, which is not only limited to stockpiling but actively sets down a path of shifting reliance on domestic productions and recycling REE, to India who too has been at the receiving end of China’s unpredictable restriction policies and now through the ‘National Critical Mineral Mission’ of 2025 aims to arm itself through greater exploration of its reserves with Dedicated Rare Earth Corridors and bolstering its production capabilities especially in the midstream where a more dedicated concern is required. The other significant step has been diversifying partnerships, a clear example being the Quad Critical Minerals Initiative, which is aiming to meet the objectives of reducing the single country reliance while simultaneously overcoming institutional lag, part of which is related to each of its members trying to reach the goal on their own while trying to embed themselves at the top of a ‘new’ value chain as possible.  

As these overlapping policies try to secure the supply chain of REE, real success will remain in trying to sustain them against the race of time. As the EU ‘Critical Raw Materials Act’ note part of its goal, that by 2030 no more than 65 per cent of REE should be sourced from a third country, which means that only through long term resilience can this become commercially and strategically viable, if one keeps in mind the embedded dependence that prompted the efforts in the first place.   

The Quiet Alternative: Why India’s Modest Energy Diplomacy Is Gaining Ground in Africa as Bigger Pledges Stall

By: Khushbu Ahlawat, Consulting Editor, GSDN

India-Africa Cooperation: Source Internet

Africa’s energy problem has never really been a shortage of promises. In the fourteen years since the first big Western climate-finance package was unveiled for the continent, pledges have piled up faster than power lines. What has not kept pace is delivery. The International Energy Agency’s most recent World Energy Investment report puts a hard number on the gap: global energy spending is on track to hit roughly $3.4 trillion in 2026, and Africa — home to nearly a fifth of humanity — will capture only about 3 percent of it, some $110 billion, even as almost 590 million Africans still live without electricity. Closing the access gap alone would require an estimated $150 billion over the next decade, more than $15 billion a year; actual tracked financing for new connections has recently run below $2.5 billion annually. Against that backdrop, it is worth asking not just who is offering Africa money for its energy transition, but whose money is actually landing.

That question has become sharper in the past eighteen months because the most publicised Western answer — the Just Energy Transition Partnerships struck with South Africa, Indonesia, Vietnam and Senegal from 2021 onward — has run into serious trouble. And it is in the space opened up by that trouble that a quieter, less heralded model of cooperation, built by India over three decades of trade and lines of credit, is starting to look more durable than its modest scale would suggest.

Where the marquee model stalled

South Africa’s JETP was the template. Announced at COP26 in Glasgow in 2021 with an initial $8.5 billion pledge from a group of wealthy governments, it was billed by President Cyril Ramaphosa as a watershed and by then-UK Prime Minister Boris Johnson as a “game-changing partnership.” Three more countries signed similar deals over the following two years, and the combined pledges across all four eventually approached $47 billion.

The follow-through has been thin. Independent trackers found that as of late 2024, only around $308 million of grant-funded South African projects had actually reached implementation, out of a pledge that had by then grown to $13.8 billion on paper; across all four JETP countries, only about $18.6 billion of the roughly $47 billion envelope had reached legal close by April 2026 — a completion ratio under 40 percent, more than four years into the programme. Much of what has moved is not new decarbonisation spending but commercial loans and policy financing, some of it redirected to projects, like Jakarta’s mass transit system, that were never really part of the original climate remit. Then, in March 2025, the United States formally withdrew from South Africa’s JETP altogether, pulling out $56 million in grants and $1 billion in prospective development-finance lending. The remaining partners issued a statement of continued commitment, but the exit of the JETP’s largest non-European backer was a blunt signal about how fragile these pledges can be once domestic political winds shift in donor capitals.

None of this makes JETP-style finance worthless — where it has landed, it has funded real grid and renewables work — but it has exposed a structural mismatch: large, headline pledges built on complex multilateral governance, denominated mostly in commercial or semi-concessional debt, disbursed against conditions that assume institutional capacity African utilities frequently do not have. China’s alternative, heavy infrastructure lending under the Belt and Road umbrella, has filled some of that gap with speed, but at the cost of debt burdens that have become politically toxic in several recipient states, and with far less emphasis on the distributed, off-grid solutions that reach the rural and peri-urban populations who make up the bulk of Africa’s 590 million unconnected people.

The case for a third, smaller model

India’s energy engagement with Africa was not designed as an answer to either of these problems — it grew out of a much older trade and development relationship, with bilateral trade now running at roughly $82–100 billion a year and cumulative Indian investment on the continent near $80 billion since 1996. But its architecture happens to sidestep both of the failure modes visible in the JETP and Belt-and-Road experiences.

The financing runs primarily through concessional lines of credit under the Indian Development and Economic Assistance Scheme, administered by the Exim Bank of India, supplemented by grant-funded technical training through the Indian Technical and Economic Cooperation programme. New Delhi has extended more than 190 such lines of credit worth over $10 billion to 41 African countries, a large share of it directed at power generation, transmission and rural electrification — smaller in aggregate than either the JETP pledges or Chinese infrastructure lending, but structured to move faster because it does not depend on assembling a multi-donor governance committee for every disbursement.

The technology side leans in the same direction. Where JETP financing has gone disproportionately toward utility-scale grid and coal-transition projects, India has built its own domestic renewable programme — over 50 percent non-fossil share of installed power capacity, reached five years ahead of its own climate-pledge target, alongside roughly 172 gigawatts of annual solar-module manufacturing capacity — around decentralised, household- and farm-level deployment. The rooftop solar scheme PM Surya Ghar had installed more than four million systems domestically by August 2026, and the PM-KUSUM programme has done similar work subsidising solar irrigation pumps for farmers. Both are now being pitched, through the International Solar Alliance that India co-founded with France, as templates for African electrification. The ISA now counts roughly 39 African members, and is channelling that experience through instruments like the MIGA-ISA Solar Facility and a partnership with the African Development Bank’s Desert to Power initiative — positioning India less as a builder of large plants and more as a supplier of de-risking finance and small-footprint technology suited to dispersed, weak-grid populations, which is precisely the segment the IEA’s numbers show is being underserved by both Western and Chinese capital.

Two different countries, two different tests

South Africa and Ethiopia illustrate how differently this model plays out depending on what a partner country actually needs.

South Africa is the industrial test case. As a fellow BRICS member, it deals with India roughly as a peer rather than as an aid recipient, and the relationship has moved toward critical minerals and green hydrogen — South Africa’s platinum-group metals, used in electrolysers, are a natural complement to India’s own hydrogen ambitions, which depend on imported catalysts and battery inputs. The India–Southern African Customs Union Preferential Trade Agreement, signed in August 2026, is explicitly framed around securing supply of platinum-group metals, manganese and copper for India’s electric-vehicle and hydrogen industries, while a BRICS Joint Report on Hydrogen Value Chains released this year singles out South Africa and India as having complementary solar, wind and mineral endowments. This is a genuinely two-way commercial relationship, not a donor-recipient one, which is also why it sidesteps a criticism increasingly levelled at South Africa’s JETP — that it asks the country to choose between industrial growth and decarbonisation. India’s engagement, by contrast, treats South African industrialisation and green-hydrogen ambition as the same project.

Ethiopia is the harder test, because it is the kind of low-capacity, high-need market where all three financing models — JETP-style pledges, Chinese debt, and Indian concessional credit — have struggled in different ways. More than 45 percent of Ethiopians still lack electricity access, and the grid is roughly 90 percent hydropower-dependent, which leaves the country’s power supply exposed to drought. India elevated its relationship with Addis Ababa to a “strategic partnership” in December 2025, with energy and critical minerals named as priority areas, and Ethiopia has become one of the largest recipients of Indian development credit on the continent, alongside a roughly tenfold increase over the past decade in training slots offered to Ethiopian officials under the ITEC programme. Ethiopia was also among the earliest African members of the International Solar Alliance, with rooftop solar and solar irrigation pumps identified as the most transferable pieces of India’s domestic experience.

But Ethiopia is also where the limits of India’s concessional-lending model are most visible. In February 2024, the Indian government had to pay Exim Bank roughly ₹9,014 crore (close to $1.1 billion) after invoking sovereign guarantees on a set of underperforming lines of credit across several African markets — a category that reportedly included Ethiopian projects. That episode is a useful corrective to any narrative that presents Indian development finance as inherently more effective than its Western or Chinese counterparts. It is not immune to the same problem that has slowed JETP implementation: weak project preparation, patchy execution capacity on the recipient side, and financing structures that assume a level of institutional follow-through that does not always exist. India’s advantage is not that its credit always performs. It is that the amounts are smaller, the bureaucracy is thinner, and the technology is often simple enough — a rooftop panel, a solar pump — that failure is more localised and less likely to derail an entire multi-billion-dollar partnership the way stalled coal-plant financing has slowed the JETPs.

Scaling through multilateral platforms, not bilateral ambition alone

India’s own numbers make clear it cannot close Africa’s financing gap by itself. Cumulative Indian investment of roughly $80 billion since 1996, spread across four decades, is smaller than the annual investment the IEA says is needed just to close the electricity-access gap. What India brings instead is a set of multilateral levers it can pull as the 2026 chair of BRICS. The bloc’s New Development Bank has already shown what this can look like in practice, approving a $180 million loan to South Africa’s Eskom in 2019 for grid integration of renewables; a newly launched BRICS Digital Centre of Excellence for Smart Grids and Energy Storage is meant to extend that kind of technical cooperation across the bloc’s African members, including South Africa and Ethiopia, following commitments made at the June 2026 BRICS Energy Ministers’ meeting under India’s presidency. India’s own Global Biofuels Alliance, of which South Africa is a member, offers a further channel that could matter for a country like Ethiopia, where reliance on traditional biomass for cooking remains widespread and where the IEA estimates the clean-cooking financing gap for sub-Saharan Africa alone runs to roughly $4 billion a year.

None of this amounts to India displacing Western or Chinese capital in Africa; the scale gap is too large for that to be a realistic ambition, and it is not the one New Delhi appears to be pursuing. What India’s approach does offer, at a moment when the marquee Western model has just lost its largest backer and Chinese debt-financed infrastructure has generated its own political backlash, is a demonstration that smaller, faster-moving, technically modest cooperation — concessional credit lines administered without a multi-donor steering committee, and decentralised solar technology suited to the populations who are hardest to reach — can deliver results in the specific segment, off-grid and rural electrification, where the biggest pledges have struggled the most.

The limits of a model built on modesty

There is a temptation, in comparing India’s record against a stalled JETP and a reputationally damaged Belt-and-Road, to overstate the case for the Indian approach simply because it has generated fewer high-profile failures. That comparison is partly an artefact of scale: a $10 billion credit book spread across 41 countries produces far less catastrophic-sounding news than a single $47 billion multi-country pledge falling short, even if the smaller programme’s success rate, project for project, turns out to be no better. The Exim Bank’s need to invoke sovereign guarantees on underperforming loans in 2024 is proof that Indian concessional finance carries the same underlying risks — poor project preparation, weak recipient-side execution capacity, currency and political risk — that have slowed every other model of development finance operating on the continent. What differs is exposure: because Indian lines of credit are disbursed in smaller tranches to individual countries rather than bundled into headline multi-billion-dollar partnerships, a stalled project in one country does not derail a global narrative the way South Africa’s JETP shortfall has coloured perceptions of the entire Just Energy Transition concept.

There is also a question of durability that cuts the other way from the JETP comparison. Western climate pledges are vulnerable to shifts in domestic politics, as the US withdrawal from South Africa’s JETP demonstrated — but Indian development finance is not immune to its own version of that risk. The Exim Bank’s LOC guarantees are ultimately backed by the Indian exchequer, and a government facing its own fiscal pressures, or a shift in New Delhi’s strategic priorities toward, say, the Indo-Pacific or its own domestic energy build-out, could just as easily see African lending slow. What has protected the relationship so far is less institutional permanence than the fact that India’s stakes in Africa’s critical minerals, and its interest in African markets for its own solar manufacturing base, give it a commercial reason to stay engaged that is somewhat more durable than a purely aid-driven relationship would be.

That commercial logic, more than any claim to a superior development model, is probably the more honest explanation for why India’s Africa engagement has kept expanding even as Western climate finance has stalled and Chinese lending has become more selective. New Delhi needs South African platinum-group metals and Ethiopian rare-earth potential for its own battery and hydrogen ambitions; it needs African markets to absorb the excess capacity of a solar-manufacturing sector it has built up to roughly 172 gigawatts a year. Framing this as development cooperation is not wrong, but it understates how much of the relationship’s resilience comes from mutual commercial interest rather than altruism — which may, in the end, be exactly why it is proving more durable than pledges that depended on the goodwill of donor electorates thousands of miles away. Whether that model can be scaled without losing the speed and simplicity that make it work — and without succumbing to the same execution risks that undid a chunk of its own lending in Ethiopia — is the real test of India’s 2026 BRICS presidency, and of its Africa policy for the rest of the decade.

The G7’s Democracy Problem: Why 2026 Is the Wrong Year to Formalise a D10

By: Khushbu Ahlawat, Consulting Editor, GSDN

Bharat Mandapam, New Delhi, ahead of 18th BRICS SUMMIT: Source Internet

For a concept that has been “about to happen” for eighteen years, the idea of a D10 — a formal club of ten leading democracies built around the G7 — keeps resurfacing at exactly the moments when the world’s democracies feel most outnumbered. This September is one of those moments. Within the space of ten days, New Delhi hosted the 18th BRICS summit with eleven member states and a clutch of partner countries at its table, the Shanghai Cooperation Organisation had already met in Bishkek, and the UN General Assembly’s marathon session in New York opened against the backdrop of a much-anticipated Trump-Xi meeting on artificial intelligence. Against that backdrop, it is tempting to look at the G7’s expanding guest list — India, Australia, South Korea and others showing up summit after summit — and conclude that an informal D10 already exists in all but name, and that formalising it is simply a matter of political will.

That is a more contestable claim than it looks. A closer look at how the G7’s 2026 summit in Évian was actually assembled suggests the opposite lesson: the “coalition of democracies” that shows up at G7 tables each year is not consolidating into a stable ten-member club. It is doing something messier — expanding, contracting and reshuffling by host-country preference, which is precisely why, after nearly two decades of advocacy, no G7 government has been willing to give it a name.

An idea older than most of its supporters remember

The D10 concept did not emerge from a single dramatic proposal. It was assembled in stages, each one responding to a different anxiety about the durability of the post-Cold War order. Its earliest articulation came from within the US State Department’s policy-planning staff around 2008, where officials began sketching what a values-based grouping of the G7 plus Australia, India and South Korea might look like as a complement to — not a replacement for — existing institutions. The idea then migrated to the think-tank world: the Atlantic Council opened a “D10 Strategic Forum” in 2014, running informal, official-level dialogues that have continued annually since, drawing in observers from India, Indonesia, Poland and Spain along the way.

It took a very specific technological panic to turn the idea from a seminar topic into a headline. In 2020, as governments across Europe debated whether to strip Huawei out of their 5G networks, British Prime Minister Boris Johnson floated a “Democracy 10” as a vehicle for jointly developing alternative telecoms suppliers — a proposal to use collective democratic weight to break a single company’s, and by extension a single state’s, grip on critical infrastructure. Johnson subsequently used the UK’s G7 presidency to invite the leaders of Australia, India and South Korea (along with South Africa) to the 2021 Cornwall summit as guests, a pattern that has essentially held ever since, chair by chair.

What is notable is how narrow the original justification was. The D10 was conceived as a project about supply chains and standards — 5G first, later semiconductors, critical minerals and AI governance — not as a security alliance or a diplomatic bloc with its own foreign policy. That framing matters for judging what has, and has not, actually converged in the years since.

The convergence case, and its limits

There is a real trend line to point to. At the 2023 Hiroshima summit, G7 leaders spent unusual amounts of time on economic coercion and supply-chain resilience — an implicit China conversation conducted mostly in the language of “de-risking” rather than decoupling. At Kananaskis in 2025, the grouping launched a critical-minerals action plan and pushed forward on AI governance with Australia, India and South Korea in the room, prompting commentary that every member of the Quad — the US, Japan, Australia and India — had effectively sat at a single table. Canada’s Mark Carney made the strategic logic explicit at the time, describing India’s inclusion in terms of its centrality to global supply chains rather than shared political values, which is itself telling about how the invitations are actually justified.

But 2026 complicates this narrative more than it confirms it. France’s Évian summit in June, held under President Emmanuel Macron, did not simply reconvene the “G7 plus three” formula. Paris invited five partner countries to the Sherpa track and the leaders’ sessions — Brazil, Egypt, India, Kenya and South Korea — while Australia, a charter member of every D10 proposal since 2008, was left off the guest list entirely. In its place came Kenya and Egypt, neither of which features in any version of the D10 concept, plus a separate cluster of Gulf and Middle Eastern leaders (Qatar, Saudi Arabia, the UAE, and Ukraine) invited for sessions specifically framed around the war in Ukraine and Middle East stability rather than democratic solidarity. The unifying theme of Évian, according to the French hosts, was “Forging New Partnerships and Rebuilding International Solidarity” — a title that speaks to French diplomatic priorities around Africa, the Gulf and the Global South, not to a consolidating club of democracies.

This is not a minor scheduling quirk. It reveals what the G7 outreach list has actually become under successive presidencies: a mirror of each host nation’s own foreign-policy priorities, redrawn every year. Germany’s 2022 and Italy’s 2024 presidencies invited India alone, notably leaving out Australia and South Korea — a choice widely read in Berlin and Rome as reluctance to appear to be building an anti-China bloc on European soil. France’s 2026 list swapped in African and Gulf partners instead of the Indo-Pacific triad. The pattern is not a democracy club slowly hardening into ten permanent seats; it is a rotating cast whose composition tracks whichever G7 capital happens to be hosting, and whatever crisis — Ukraine, the Middle East, African debt, AI — that capital wants to headline that year.

India is the one genuine constant. It has now attended G7 outreach sessions in some form for seven consecutive years, and Prime Minister Narendra Modi used his 2026 Évian appearance to press a Global South argument about trust deficits and underrepresentation in global governance — a message aimed as much at reforming existing institutions as at joining a new democratic bloc. That consistency is real, and it is the strongest empirical case that India, at least, has become indispensable to the G7’s outward-facing agenda. But indispensability to one country’s invitation list is different from the existence of a ten-member coalition with defined membership, and the 2026 guest roster is proof that the “ten” in D10 is, at best, aspirational.

Meanwhile, the rival bloc keeps meeting too

It is worth setting this against what happened in New Delhi the same week this piece went to print. The 18th BRICS summit, chaired by India under the banner “Building for Resilience, Innovation, Cooperation and Sustainability,” produced a New Delhi Declaration running to some 140 paragraphs, adopted unanimously by all eleven members despite sharp internal disagreements — the summit had to paper over divisions between members on both sides of the Iran conflict and could not bring itself to name the United States directly even while criticising tariff wars. Xi Jinping and Vladimir Putin were both present. The declaration touched on local-currency payment systems, the New Development Bank, AI governance and counter-terrorism language that pointedly referenced the 2025 Jammu and Kashmir attack — a notable diplomatic win for India within a bloc it does not fully trust.

The point is not that BRICS is more coherent than the G7’s democratic outreach — by most independent readings, BRICS remains a coalition of convenience held together more by shared grievance against Western-dominated institutions than by any positive common project, and analysts described this year’s outcome as “modest” precisely because so many members had reason to want it to fail. The point is that both blocs are, in their own ways, loose and improvised, and India sits inside both of them simultaneously, extracting leverage from each without formally committing to either. A formal D10 would require India to make a choice that its own diplomacy has spent a decade avoiding.

Why formalisation keeps stalling — and why that might be the right call

None of this means the D10 idea is worthless. The functional cooperation it has produced — on critical minerals, on 5G and telecoms security, increasingly on AI governance — is real and useful, and it has grown steadily each summit cycle regardless of what the grouping calls itself. But three structural obstacles explain why, after eighteen years, no G7 government has actually proposed making it permanent.

The first is continental Europe’s persistent unease. Germany and Italy’s decisions to invite India without its Indo-Pacific partners, and France’s 2026 substitution of African and Gulf outreach for the Australia-South Korea axis, both reflect a European preference for keeping China-adjacent messaging implicit rather than explicit. A named D10, with China unmentioned but unmistakably the subtext, would be harder to keep deniable.

The second is the unpredictability of the United States itself under the current administration, whose bilateral, transactional approach to allies sits uneasily with the idea of binding itself into a standing multilateral body with fixed membership and shared positions — the same unpredictability that has scrambled G7 unity on tariffs and Ukraine policy over the past two years.

The third, less discussed, is opportunity cost. Every year the G7’s outreach list is redrawn to fit that year’s crises — Ukraine and the Middle East in 2026, critical minerals and AI in 2025 — democracies retain the flexibility to build ad hoc coalitions suited to the problem at hand, rather than being locked into a fixed roster that might not fit the next crisis. Kenya and Egypt’s presence at Évian, driven by African debt and Middle East diplomacy rather than any democratic credential test, is a feature of that flexibility, not a bug to be engineered away.

A named D10 would trade this adaptability for clarity and symbolic weight — useful currency in a summit season this crowded, but not obviously worth the diplomatic cost of formally declaring a democratic bloc at a moment when the G7’s own hosts cannot agree on who belongs in it. The more realistic near-term outcome is what has actually been happening: growing functional cooperation on specific files — minerals, AI standards, supply-chain resilience — carried out by whichever subset of democracies has skin in that particular game, dressed up each year in whatever coalition the host capital finds diplomatically convenient. That may be less tidy than a named club of ten. It has also, so far, proved more durable than any of the formal proposals sitting in Atlantic Council file drawers since 2014.

What a more honest middle path looks like

If naming the coalition is politically premature, the alternative is not to abandon the project but to be more precise about what is actually being built. Advocates on both sides of the Atlantic have tended to conflate two different things: a security-and-values alliance modelled loosely on NATO’s political solidarity, and a narrower, technocratic coalition built around specific chokepoints in the global economy — telecoms equipment, semiconductor supply chains, rare-earth processing, AI safety standards. The second project has actually delivered results, from the critical-minerals action plan agreed at Kananaskis to the emerging AI-governance conversations that dominated both Kananaskis and Évian. The first project — a values-based alliance with a permanent secretariat, of the kind the Atlantic Council sketched out as far back as 2019 — has delivered almost nothing, precisely because it asks capitals to commit to a shared foreign policy they do not actually share, on China, on Russia, or on how confrontational to be with either.

Treating these as one project is what keeps stalling formalisation. A functional D10 — a standing, sherpa-level coordination mechanism for supply-chain and technology-standards cooperation among a flexible set of capable economies, without the language of a democratic bloc or a shared security posture — would be far easier for continental Europe to sign onto, since it avoids the anti-China framing that Berlin, Rome and Paris have each resisted in different summit cycles. It would also suit India, which has consistently sought the economic and technological benefits of closer G7 alignment while refusing anything that reads as bloc alignment against Russia or China, given its BRICS membership, its dependence on Russian energy and defence equipment, and its own unresolved border tensions with Beijing that require careful management rather than open confrontation.

This is, in effect, close to what has already been happening under different names each year — but making it durable would mean giving the functional cooperation a standing institutional home, independent of whichever country holds the rotating G7 presidency, so that critical-minerals and AI-governance work does not have to be re-negotiated and re-justified every twelve months depending on whether the host capital that year prioritises the Indo-Pacific, Africa or the Gulf. That is a far more modest ambition than the “alliance of democracies” that Atlantic Council reports and British prime ministers have periodically proposed. It is also, on the evidence of Évian’s scrambled guest list, a great deal closer to what G7 governments are actually willing to build.

Salami-Sliced Legitimacy: How the World Is Normalising the Taliban Without Ever Formally Saying So? 

By: Khushbu Ahlawat, Consulting Editor, GSDN

Salami-Sliced Legitimacy: Source Internet

Introduction

In June 2026, Belgium granted one-day visas to a five-member Taliban delegation so it could hold talks with European Union officials in Brussels — the first time since the group’s 2021 return to power that an official Taliban delegation set foot on European soil for direct engagement with the bloc. The European Commission was careful to insist the meeting, focused on migration and the repatriation of Afghan nationals, did not amount to recognition. That insistence, however, is becoming a familiar refrain across capitals that have, in practice, been moving toward normalisation with Kabul for years while studiously avoiding the word that would make it official. The EU’s migration-driven engagement is not an isolated European story; it is the latest data point in a broader, remarkably consistent global pattern — recognition arriving in instalments, justified each time by narrow technical necessity, while the cumulative diplomatic reality shifts underneath the official position of non-recognition.

This pattern deserves to be examined as a pattern, because looking at any single country’s engagement in isolation misses what is actually happening: a coordinated-in-effect-if-not-in-intent, multi-track normalisation of the Taliban that has left the group governing with more international engagement in 2026 than at any point since 2021, even as the formal diplomatic status of the Islamic Emirate remains unresolved almost everywhere.

The Baseline: Russia’s Formal Break from the Pack

Russia crossed the threshold nobody else has, on 3 July 2025, becoming the first state to formally recognise the Taliban as Afghanistan’s legitimate government, following the Russian Supreme Court’s decision to remove the group from its list of terrorist organisations that April. Moscow’s justification was explicitly functional rather than ideological: shared concern about Islamic State-Khorasan Province, which claimed responsibility for the March 2024 Crocus City Hall attack that killed 145 people, alongside stated interest in trade and economic opportunities in energy, transport, agriculture, and infrastructure. Bilateral trade between Russia and Afghanistan had already reached roughly $1 billion in 2024 even before formal recognition, with Moscow functioning as a primary supplier of oil, gas, and wheat to Afghanistan throughout the period when the relationship was still technically unrecognised.

What is notable about Russia’s move is less the recognition itself than how unremarkable it turned out to be diplomatically. China’s Ministry of Foreign Affairs welcomed the decision within a day, describing Afghanistan as one that “should not be excluded from the international community” — a statement that reads less like surprise at an ally’s unilateral step and more like a chorus member picking up a cue.

China’s Quieter Version of the Same Move

China had, in fact, already taken the substantive step eighteen months earlier without using the word “recognition.” In December 2023, Beijing became the first country to accredit a Taliban-appointed diplomat as an ambassador — full ambassadorial status, the highest rung of diplomatic representation short of the word “recognition” itself — while its foreign ministry simultaneously and explicitly denied that the move constituted recognition. This is the precise manoeuvre that has since become the template followed, with local variations, by the United Arab Emirates, Uzbekistan, Türkiye, and Pakistan, all of which have upgraded their diplomatic relations with Kabul to ambassadorial level while maintaining the same formal disclaimer.

China’s approach has been consistent with its broader Belt and Road logic: engagement calibrated to protect and expand infrastructure and investment interests, while security concerns about Uyghur militant groups operating from Afghan soil give Beijing the same counter-terrorism justification Moscow has used. At least seventeen countries now maintain embassies in Taliban-run Afghanistan, and Taliban-appointed diplomats represent the country in most Asian capitals, generally at the chargé d’affaires level — a rank just below full ambassador that has become the diplomatic community’s preferred way of maintaining substantive relations while keeping a technical fig leaf over the recognition question.

India’s Parallel Track: From Evacuation to Embassy

India’s trajectory illustrates the pattern’s incremental logic especially clearly, because it started from the furthest distance. New Delhi evacuated its diplomats from Kabul entirely in August 2021 and cancelled visas for Afghan citizens, reflecting decades of Indian wariness toward a Taliban movement historically backed by Pakistan’s intelligence establishment. Within a year, though, India had quietly redeployed a “technical team” to Kabul to coordinate humanitarian aid delivery — food and medicine — without any of the political engagement that would follow later.

The real shift began on 8 January 2025, when India’s Foreign Secretary Vikram Misri met Taliban Foreign Minister Amir Khan Muttaqi in Dubai, the first substantive high-level contact of the post-2021 era. Telephone diplomacy followed, then, in October 2025, Muttaqi made a six-day visit to India — the first by any senior Taliban official — after the UN Security Council’s sanctions committee granted him a temporary travel exemption. During that visit, India’s External Affairs Minister S. Jaishankar announced the upgrade of India’s technical mission in Kabul to the status of “Embassy of India,” while pointedly stopping short of language that would imply formal recognition of the Taliban government. India also agreed to let the Taliban post its own diplomats to the Afghan embassy in New Delhi, and by January 2026 a Taliban-nominated chargé d’affaires, Mufti Noor Ahmad Noor, had taken up that post. India’s 2026-27 budget subsequently raised Afghan aid from Rs 100 crore to Rs 150 crore, and a Taliban trade delegation led by Industry and Commerce Minister Noorudin Azizi visited India in November 2025 to discuss mining, agriculture, and infrastructure investment.

India’s own strategic logic mirrors the pattern’s functional justification elsewhere, but with a distinctly regional inflection: New Delhi’s outreach intensified precisely as Pakistan-Taliban relations deteriorated into open border clashes over Islamabad’s accusations that Kabul harbours Pakistani Taliban (TTP) militants — clashes serious enough to close the Torkham and Chaman crossings and require Qatari, Turkish, and Saudi mediation for a ceasefire in October 2025. That backdrop let India frame its embassy upgrade not merely as bilateral outreach but as positioning itself as a stabilising alternative to Afghanistan’s overreliance on Pakistan, while simultaneously working to blunt Chinese and Pakistani influence in Kabul — a reminder that even within a broadly similar pattern of engagement, each state’s specific calculus remains shaped by its own regional rivalries as much as by any shared theory about Taliban governance.

The EU’s Version: Necessity Dressed as Technicality

Set against this backdrop, the EU’s Brussels meeting looks less like a diplomatic breakthrough and more like Europe arriving, three to four years late and under domestic political duress, at a position Russia, China, India, and several Gulf and Central Asian states had already reached by other routes. The EU’s proximate driver was overwhelmingly domestic: twenty of the bloc’s twenty-seven member states have pushed for stricter migration policies and firmer legal pathways for deportations, against a backdrop of roughly one million Afghan asylum applications received between 2013 and 2024, about half of them approved — making Afghans one of the EU’s largest single migrant cohorts. Germany and Austria had already been negotiating deportations bilaterally, with Berlin going so far as to allow two Taliban officials to work inside the Afghan diplomatic mission in Berlin specifically to facilitate the process — a striking illustration of how migration management pressure can produce de facto working relationships with a government whose legitimacy the same states publicly refuse to acknowledge.

The EU’s own framing — that the talks were “technical” and did not amount to recognition — is structurally identical to the disclaimers used by Beijing after its 2023 ambassador acceptance and by New Delhi after its 2025 embassy upgrade. European Parliament member Hannah Neumann’s critique, that the talks represent political normalisation without securing any accountability from the Taliban in return, could be transposed almost word for word onto criticism of China’s or India’s engagement, and has been by human rights observers in each case.

The Facilitators: Gulf and Central Asian Corridor States

Beneath the headline moves by Russia, China, India, and the EU sits a second, quieter layer of the pattern: the Gulf and Central Asian states that have functioned less as principals and more as connective tissue, making the larger normalisation possible in the first place. Qatar’s long-standing political office in Doha, established originally as a venue for the 2020 US-Taliban talks, has since evolved into the Taliban’s default diplomatic address for engaging with the wider world — the channel through which Muttaqi’s UN travel exemptions and shuttle diplomacy are routinely arranged, including the mediation Doha provided alongside Turkey and Saudi Arabia during the October 2025 Afghanistan-Pakistan border crisis. The UAE, for its part, upgraded to ambassadorial-level relations with Kabul early in the same wave as China, and it was Emirati facilitation that produced the January 2025 Dubai meeting between India’s Foreign Secretary and Muttaqi — the meeting that effectively opened India’s own normalisation track.

Central Asian states have played an equally structural, if less visible, role. Uzbekistan has hosted Taliban delegations to discuss the proposed trans-Afghan rail link connecting Central Asia to Pakistani ports, a project that requires treating the Taliban as a stable enough counterpart to negotiate decades-long infrastructure commitments with. Turkmenistan and Tajikistan have pursued comparable, if more cautious, economic and border-management engagement. None of these corridor states has made a symbolically loaded move like Moscow’s formal recognition; instead, their contribution has been to normalise the logistics of engaging Kabul — travel routes, mediation venues, trade corridors — that larger powers then use without having to build that infrastructure themselves.

This division of labour matters because it means the normalisation pattern is more resilient than any single government’s policy choice. Even if one capital reversed course, the underlying infrastructure of Gulf mediation and Central Asian trade corridors would remain in place, available to the next state ready to take its own incremental step.

Why the Pattern Persists Despite Almost Nobody Endorsing It

What makes this global pattern notable is that it is not being driven by any state’s positive assessment of Taliban governance — the Taliban’s restrictions on women and girls, its ranking of 142nd out of 143 countries on the Rule of Law Index, and the fact that roughly seventeen million Afghans, about a third of the population, remain food insecure according to the UN World Food Programme, are acknowledged by essentially every engaging government, including Russia’s and China’s. Instead, the pattern is being driven by the simple durability of the fact that the Taliban is the only entity actually governing Afghan territory, which makes it the only available counterpart for anything states actually need done there: counter-terrorism cooperation against ISKP, deportation and repatriation logistics, mineral and infrastructure investment, or humanitarian aid delivery.

This is precisely the dynamic that produces recognition by increments rather than by declaration. Each individual government can plausibly claim its own engagement is narrowly functional and reversible — an ambassador is not recognition, an embassy upgrade is not recognition, a migration MoU is not recognition — while the cumulative diplomatic environment the Taliban operates in has unmistakably thickened since 2021: seventeen-plus embassies, ambassadorial relations with several major and middle powers, one outright formal recognition, and now direct European engagement on its own soil. The Taliban’s own foreign ministry has been explicit about reading this correctly — spokesperson Zabihullah Mujahid described Russia’s recognition as a “positive message to the rest of the world,” predicting other states would follow, and each subsequent upgrade elsewhere has functioned as exactly the kind of incremental validation Kabul is counting on.

Conclusion

The question worth asking, looking at the EU, Russia, China, and India together, is not whether any single engagement constitutes recognition — by design, none of them individually do — but whether the distinction between formal recognition and accumulated functional normalisation still matters in practice once enough states have crossed enough of these thresholds. For the Taliban, the answer is clearly no: functional engagement delivers most of what recognition would, embassies, trade, aid, counter-terrorism cooperation, and diplomatic visibility, without requiring any single government to answer politically for having granted it. For the states doing the engaging, the salami-slicing approach lets each preserve a technical position on non-recognition that increasingly describes a diplomatic reality none of them, from Brussels to Beijing to New Delhi, actually still inhabit.

Ads Blocker Image Powered by Code Help Pro

Ads Blocker Detected!!!

We have detected that you are using extensions to block ads. Please support us by disabling these ads blocker.

Powered By
100% Free SEO Tools - Tool Kits PRO